
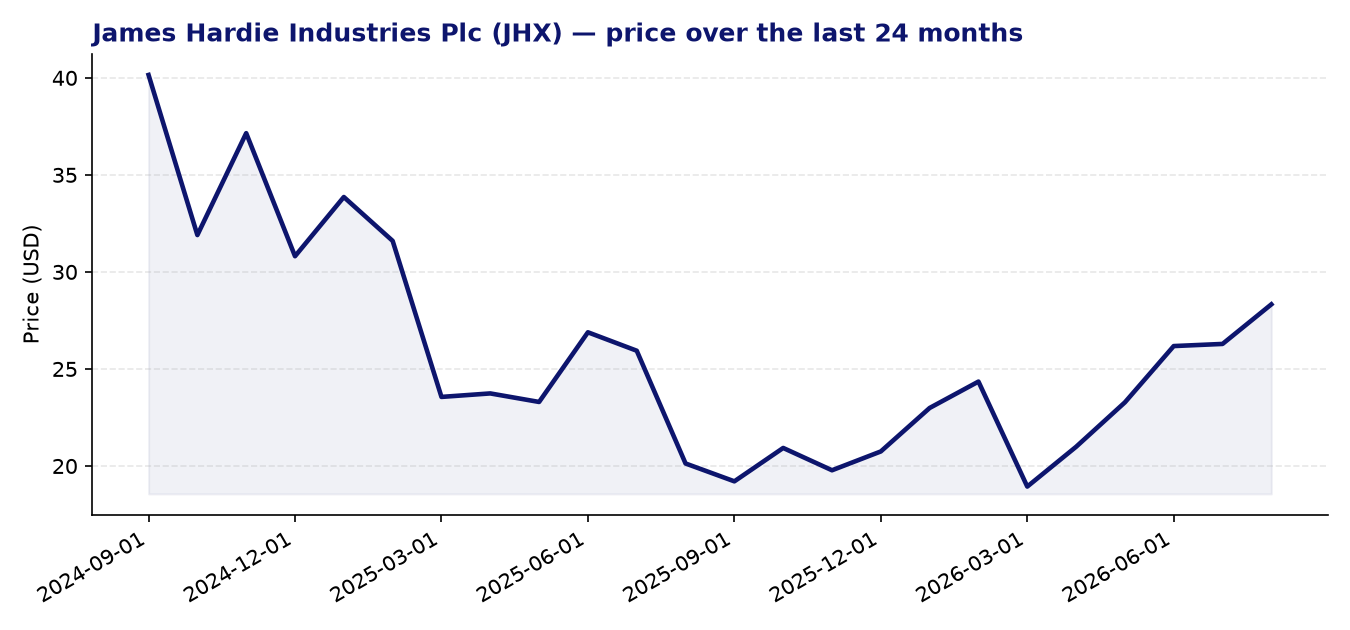
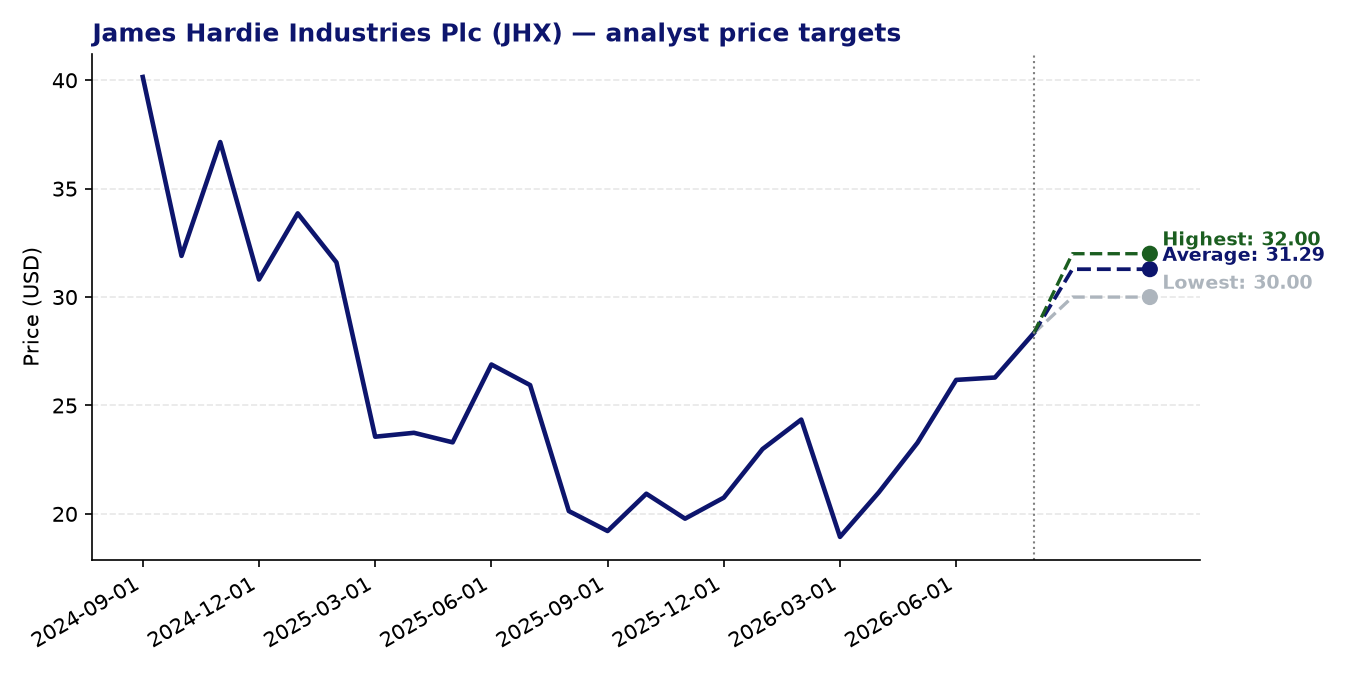
James Hardie Industries Plc (JHX) — current price: 28.32 USD | average price target: 31.29 USD | potential: +10.5%
About James Hardie Industries Plc
- James Hardie Industries, founded in 1888 and headquartered in Dublin, Ireland, is a global manufacturer of fiber cement, fiber gypsum, and cement-bonded building products sold across the US, Australia, New Zealand, and Europe.
- Its largest segment, Siding & Trim, produces fiber cement and PVC siding, trim, and mouldings under the Hardie, AZEK Exteriors, and Versatex brands for both new residential construction and repair and remodel markets.
- The Deck, Rail & Accessories segment offers wood-alternative decking, railing, pergolas, and outdoor living accessories under brands including TimberTech, ULTRALOX, and StruXure.
- In Europe, the company sells fiber gypsum and cement-bonded boards under the fermacell brand, serving residential and commercial construction and renovation markets.
- Products are distributed through specialty building products distributors, lumberyards, home improvement retailers, and directly to professional contractors and remodelers.
Recent news
- James Hardie reported preliminary first-quarter FY2027 results that came in ahead of its own guidance, with particular strength noted in both the Siding & Trim and Deck, Rail & Accessories segments.
- The company announced the appointment of Rob Sindel as an incoming director, continuing a period of measured board-level renewal.
- A ratings round-up from Motley Fool Australia included a fresh analyst view on James Hardie shares, reflecting ongoing coverage interest from the investment community.
- Separately, Zacks assigned the stock a Strong Sell ranking earlier in the year, citing uncertainty in the global housing market, though this predates the stronger-than-expected Q1 FY2027 update.
Strengths
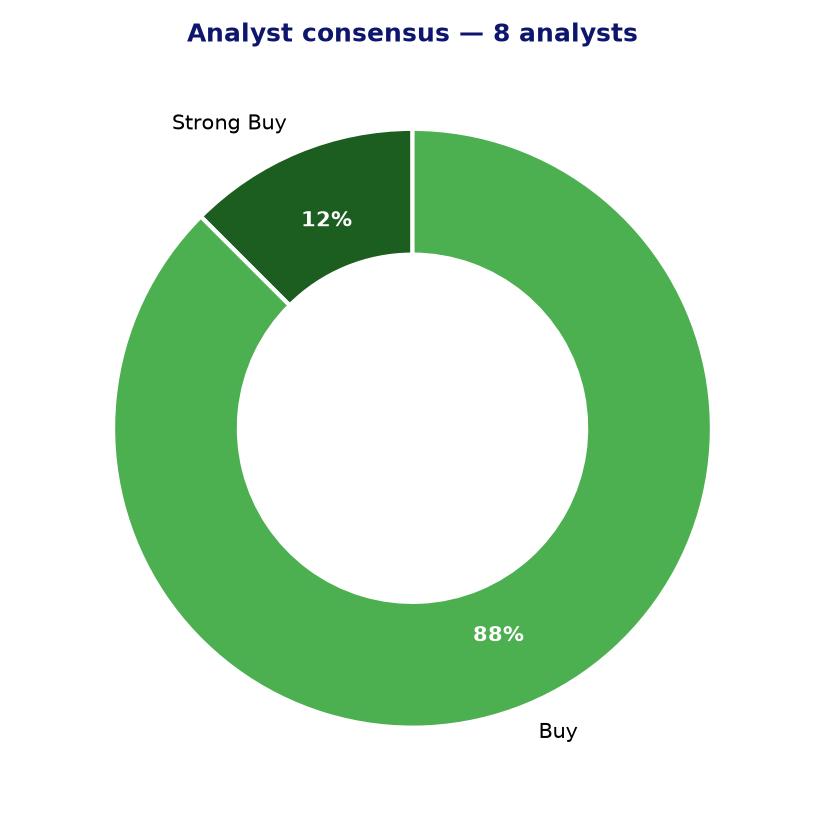
- All eight analysts covering JHX currently carry a Buy or Strong Buy rating, with no Hold or Sell recommendations, reflecting broad conviction among those who follow the stock closely.
- The consensus price target of $31.29 implies approximately 10.5% upside from the current price of $28.32, with the range of individual targets sitting in a tight $30.00–$32.00 band, suggesting reasonable analyst alignment.
- A 24-month Z-score momentum reading of 2.32 indicates that the stock has shown meaningful positive price momentum relative to its own history, which can be a constructive technical signal.
- The forward P/E of 19.06 is considerably more moderate than the trailing figure, suggesting the market anticipates a meaningful recovery in earnings power over the near term.
- Q1 FY2027 results exceeding prior guidance provide early evidence that the business may be stabilising or beginning to recover from the housing-market headwinds that have weighed on recent performance.
Points of attention and risks
- The trailing P/E of 149.08 is extremely elevated, reflecting a sharp recent decline in reported earnings and signalling that the stock’s current valuation is heavily dependent on a robust earnings recovery materialising as expected.
- EPS growth of -0.35 highlights that profitability has been under real pressure, and investors should be aware that any further delay in a housing-market recovery could push out the earnings normalisation story.
- The AAII flagged the stock as potentially overvalued on its Value Score methodology as recently as late July 2026, a reminder that valuation assessments vary meaningfully depending on the framework applied.
- James Hardie’s performance is closely tied to residential construction and repair and remodel activity globally, leaving it exposed to continued weakness in housing starts, elevated mortgage rates, or a broader economic slowdown.
- The PEG ratio of 1.29, while not extreme, is not inexpensive and leaves limited margin of safety if consensus earnings growth estimates prove optimistic.
Analyst consensus and price targets
Conclusion
James Hardie presents a mixed picture: analyst sentiment is firmly positive and the Q1 FY2027 beat suggests operational resilience, yet the stock’s stretched trailing valuation and negative recent EPS growth mean the investment case rests heavily on a housing-market recovery that has yet to fully materialise. The forward earnings multiple looks more reasonable, but it prices in a recovery that carries execution and macro risk. Investors with a medium-term horizon may find the setup interesting, though the valuation leaves little room for disappointment if conditions in residential construction remain subdued.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 05-08-2026. Not investment advice.