
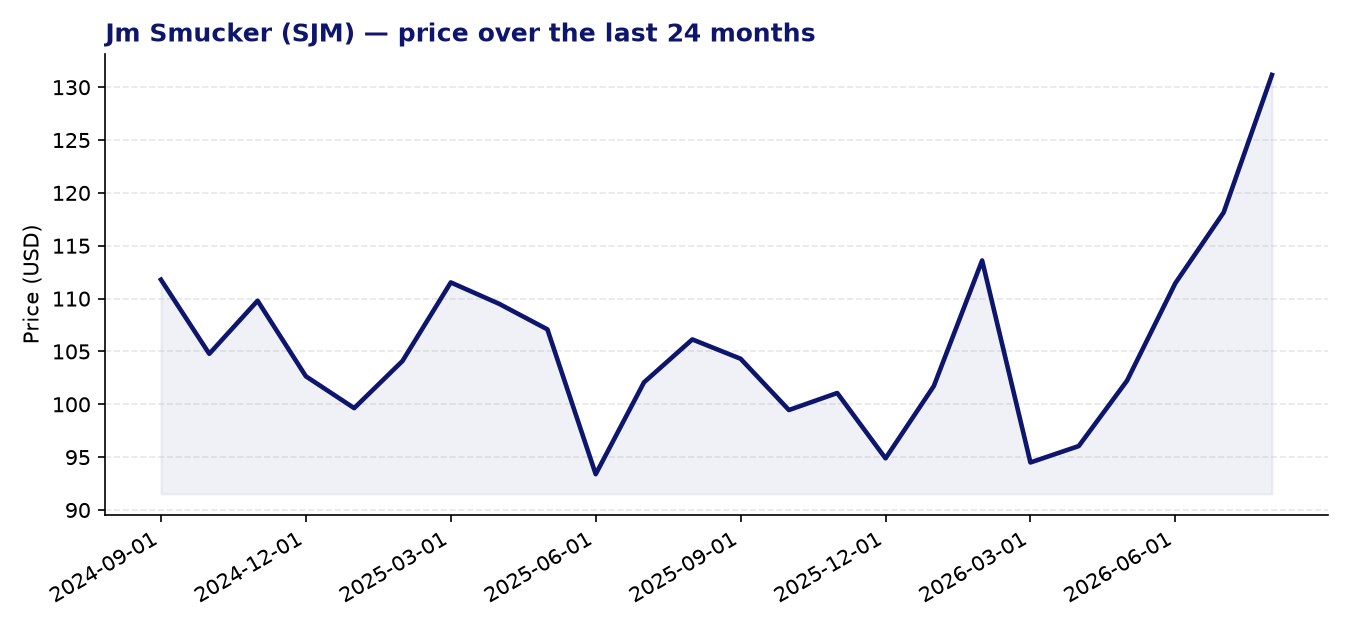
Jm Smucker (SJM) — current price: 131.16 USD | average price target: 141.44 USD | potential: +7.8%
About Jm Smucker
- J.M. Smucker, founded in 1897 and headquartered in Orrville, Ohio, manufactures and markets branded food and beverage products across the US and internationally.
- The company operates five segments: U.S. Retail Coffee, U.S. Retail Frozen Handheld and Spreads, U.S. Retail Pet Foods, Sweet Baked Snacks, and Away From Home.
- Its brand portfolio includes well-known names such as Folgers, Café Bustelo, Dunkin’, Jif, Smucker’s, Uncrustables, Meow Mix, Milk-Bone, and Hostess.
- Products are sold through a broad range of channels including supermarket chains, mass merchandisers, club stores, online retailers, pet specialty stores, and foodservice operators.
Recent news
- Smucker’s shares reached a 52-week high in late August 2026, with the move attributed in part to encouraging quarterly earnings results.
- In its second quarter of calendar year 2026, the company reported revenue of approximately $2.22 billion, representing year-on-year sales growth of around 5%.
- Analyst commentary in mid-2026 highlighted Smucker as a candidate for both growth and value-oriented investors, pointing to its diversified brand base and market positioning.
- As of mid-August 2026, the stock had gained roughly 14% over the prior six months, broadly in line with the S&P 500’s return of approximately 13% over the same period.
Strengths
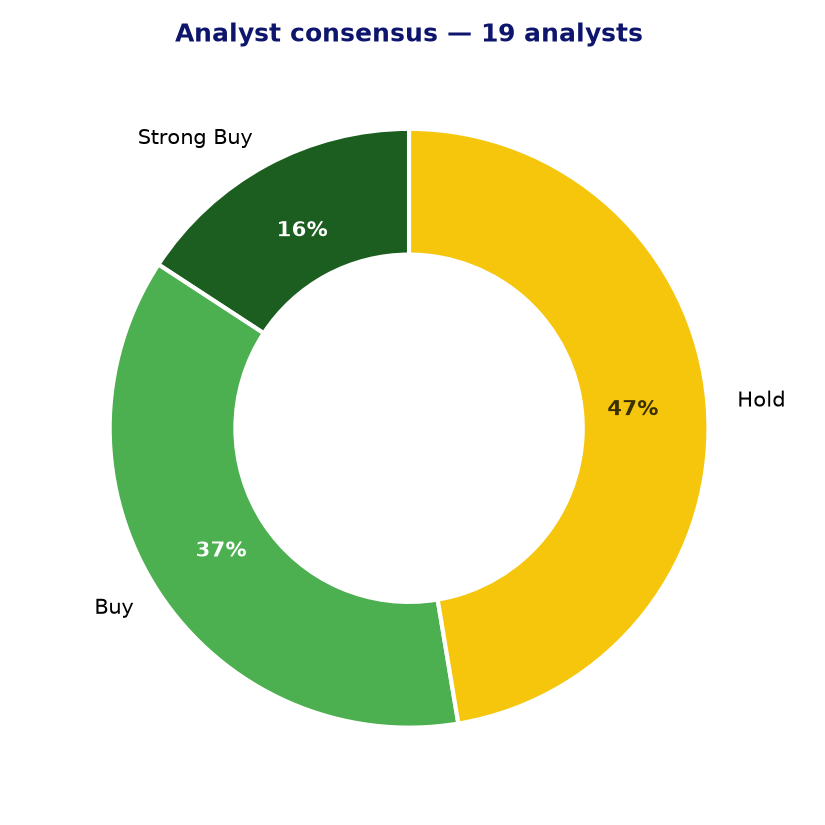
- The analyst consensus skews constructive, with 10 of 19 covering analysts rating the stock a buy or strong buy and none carrying a sell rating.
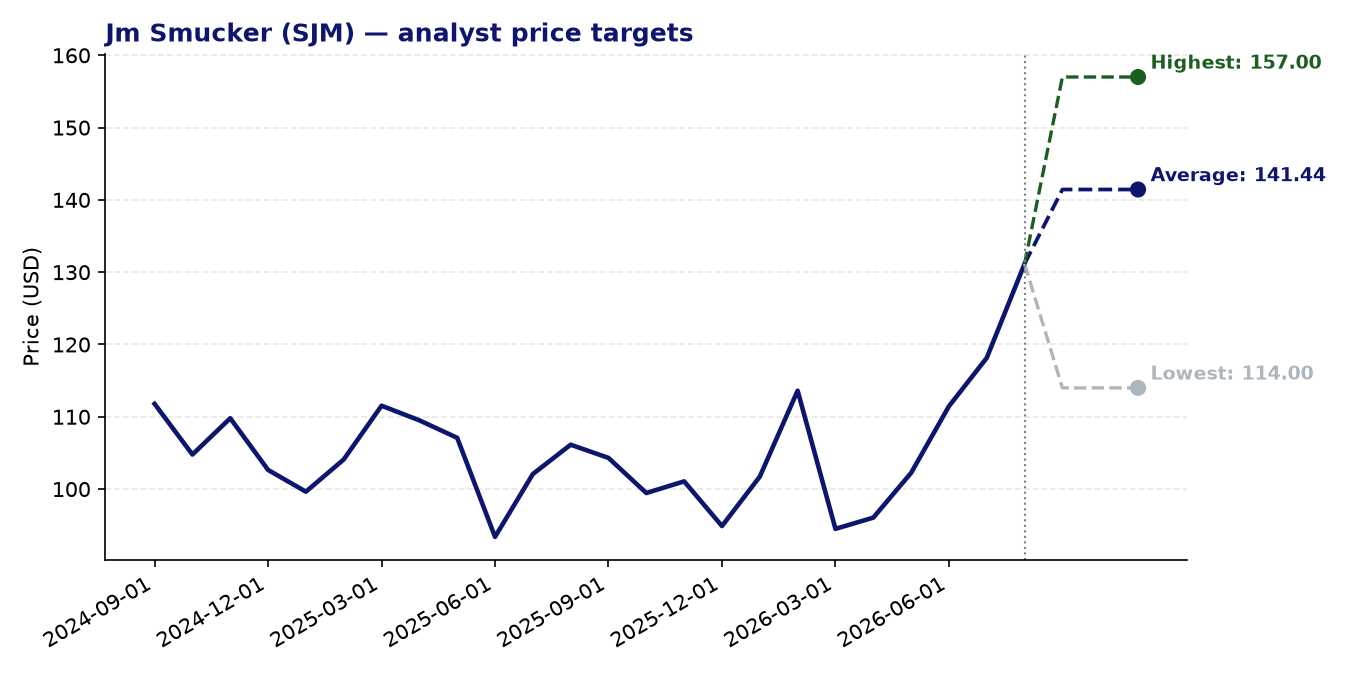
- The average price target of $141.44 implies approximately 7.8% upside from the current price of $131.16, with the highest target reaching $157.00.
- A 24-month Z-score momentum reading of 2.06 suggests the stock has exhibited meaningful positive price momentum relative to its own history.
- The forward P/E of 12.05 is considerably more modest than the trailing figure, indicating that earnings are expected to recover or grow materially in the near term.
- Revenue growth of 5% year-on-year in the most recent quarter demonstrates that the business retains pricing power and volume resilience across its diversified product categories.
Points of attention and risks
- The trailing P/E of 61.29 is elevated for a packaged foods company and suggests the current share price reflects a degree of earnings normalisation that has yet to fully materialise.
- A PEG ratio of 2.17 indicates the stock is not cheap relative to its growth profile, leaving limited margin of safety if earnings expectations are not met.
- No current EPS growth figure is available, which makes it difficult to assess the trajectory of profitability with confidence.
- The wide spread between the lowest ($114.00) and highest ($157.00) analyst price targets reflects meaningful disagreement about the company’s near-term earnings outlook.
- The packaged foods sector faces ongoing pressure from private-label competition, input cost volatility, and shifting consumer preferences toward fresh or health-oriented alternatives.
Analyst consensus and price targets
Conclusion
J.M. Smucker presents a recognisable, diversified branded food business with solid revenue momentum, a constructive analyst consensus, and positive price momentum reflected in its Z-score. However, the elevated trailing valuation and a PEG ratio above two suggest investors are paying a full price, and the absence of a current EPS growth figure introduces some uncertainty around the path to that more attractive forward multiple. Investors with a longer time horizon may find the brand depth and segment diversification reassuring, but the near-term risk-reward warrants careful attention to upcoming earnings delivery.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 31-08-2026. Not investment advice.