
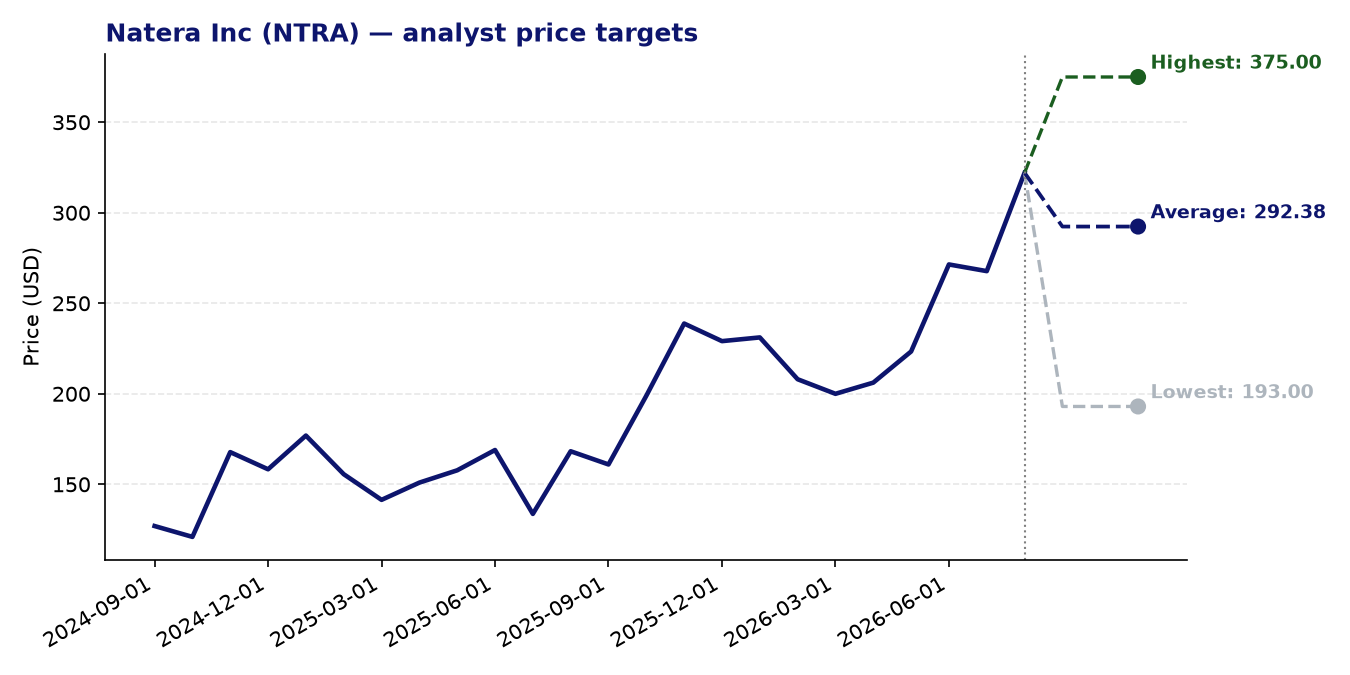
Natera Inc (NTRA) — current price: 322.10 USD | average price target: 292.38 USD | potential: -9.2%
About Natera Inc
- Natera is an Austin, Texas-based molecular diagnostics company founded in 2003, focused on developing and commercialising genetic testing services across oncology, women’s health, and organ transplantation.
- Its oncology portfolio centres on Signatera, a personalised circulating tumour DNA (ctDNA) blood test used for minimal residual disease (MRD) assessment, recurrence monitoring, and treatment response evaluation in cancer patients.
- In women’s health, Natera offers a suite of non-invasive prenatal tests (including Panorama and Vistara), carrier screening (Horizon), and miscarriage tissue analysis (Anora).
- The company also serves the organ transplant market with Prospera, a rejection-monitoring test, and the kidney disease space with Renasight, a gene panel test.
- Natera distributes its tests through a direct sales force, laboratory partners, and its cloud-based Constellation software platform, and has partnerships with BGI Genomics and Diakonos Oncology, among others.
Recent news
- Natera’s second-quarter 2026 results significantly exceeded expectations, driven by strong volume growth in Signatera, its flagship cancer-detection blood test, sending shares sharply higher.
- In late June 2026, Signatera received regulatory approval in Japan, representing a meaningful international market expansion for the test; shares rose approximately 10% on the announcement.
- The Japan approval and the Q2 earnings beat together reflect a period of notable commercial momentum for Natera’s oncology franchise within a relatively short timeframe.
Strengths
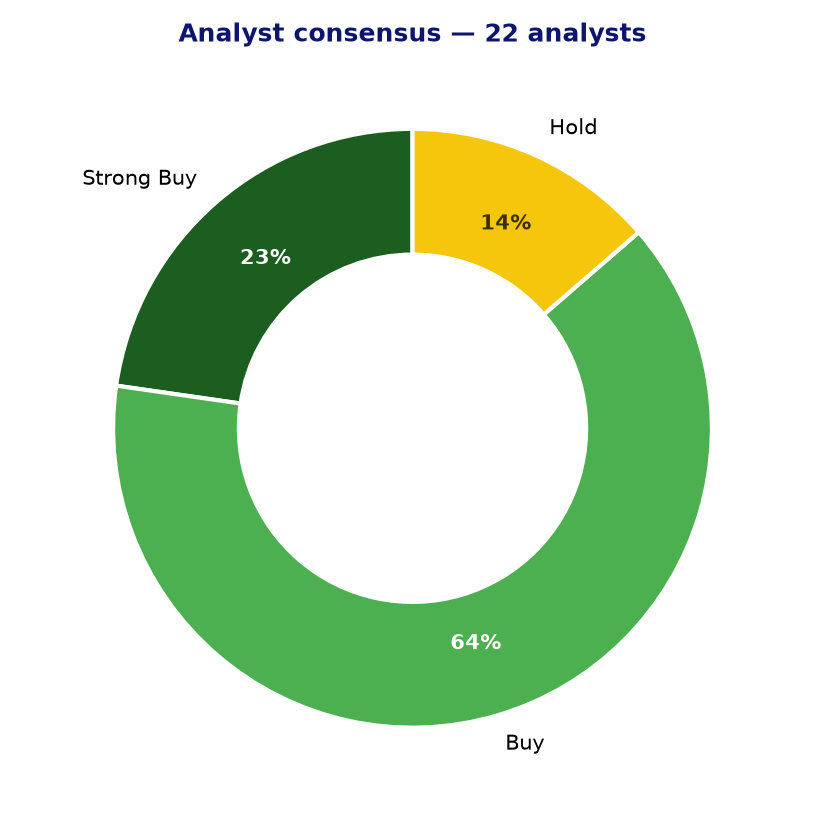
- Analyst sentiment is firmly constructive: 19 of 22 covering analysts rate the stock either Buy or Strong Buy, with no sell ratings, reflecting broad confidence in Natera’s growth trajectory.
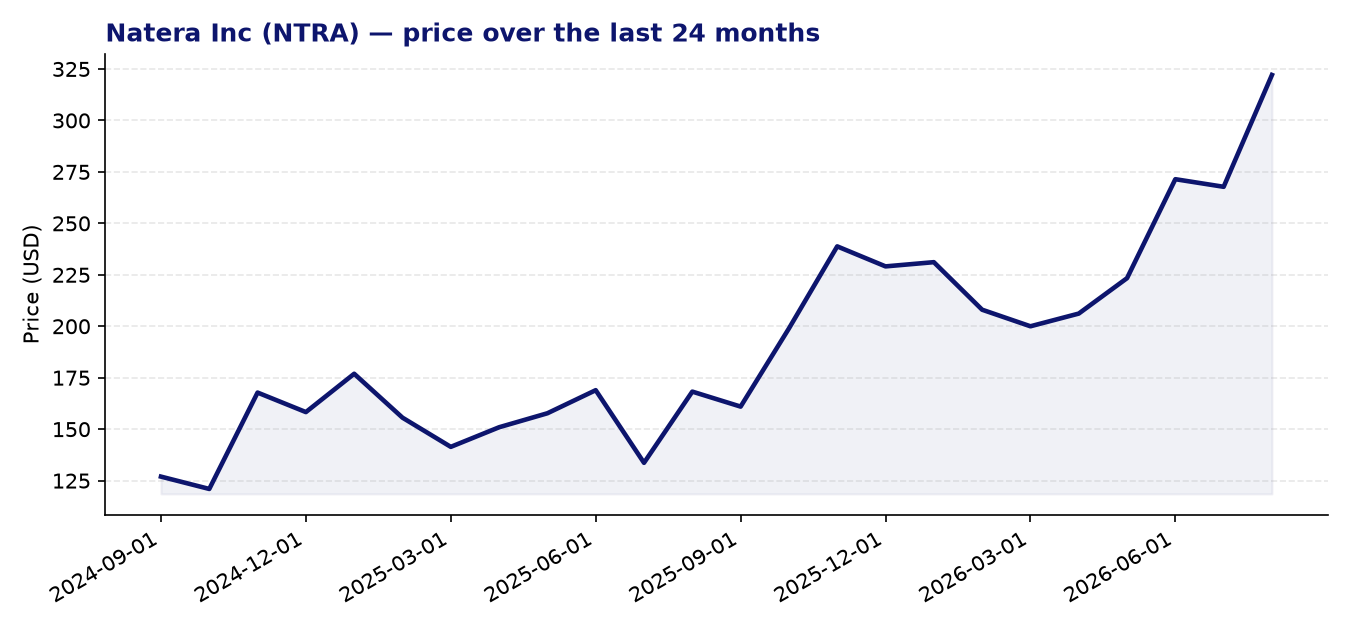
- The 24-month price momentum Z-score of 2.22 indicates that the stock has been a consistent outperformer relative to the broader market over the past two years.
- Signatera’s regulatory approval in Japan opens a substantial new geography for what is already the company’s highest-growth product, potentially accelerating international revenue contribution.
- Strong Q2 volume figures for Signatera suggest the commercial adoption of ctDNA-based MRD testing is gaining real traction among oncologists, which supports the longer-term revenue outlook.
- The breadth of Natera’s testing portfolio — spanning oncology, prenatal, transplant, and hereditary disease — provides meaningful diversification and multiple avenues for future growth.
Points of attention and risks
- The current share price of $322.10 sits approximately 10% above the average analyst price target of $292.38, suggesting the market may already be pricing in a considerable amount of near-term good news.
- Natera remains unprofitable: the forward P/E of approximately -919 and the absence of any meaningful EPS figure highlight that earnings are still deeply negative, and a clear path to sustained profitability has yet to materialise.
- The wide spread between the lowest ($193) and highest ($375) analyst price targets signals significant disagreement about fair value, reflecting genuine uncertainty around the pace and scale of the commercial ramp.
- As a high-growth, loss-making diagnostics company, Natera is sensitive to changes in reimbursement policy, particularly Medicare and private payer coverage decisions, which can materially affect test volumes and revenue.
- Following a strong recent share price run, the stock carries elevated valuation risk; any disappointment in volume growth, payer coverage, or the international rollout could lead to a sharp correction from current levels.
Analyst consensus and price targets
Conclusion
Natera occupies a compelling position at the intersection of molecular diagnostics and precision oncology, and its recent commercial milestones — including a strong earnings report and the Japanese approval of Signatera — demonstrate genuine operational progress. The overwhelming analyst consensus is positive, and momentum indicators reinforce the stock’s recent strength. However, with the share price trading above the average price target and the company still some distance from profitability, investors should weigh the undoubted long-term opportunity against a valuation that leaves limited margin for error at current levels.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 07-08-2026. Not investment advice.