
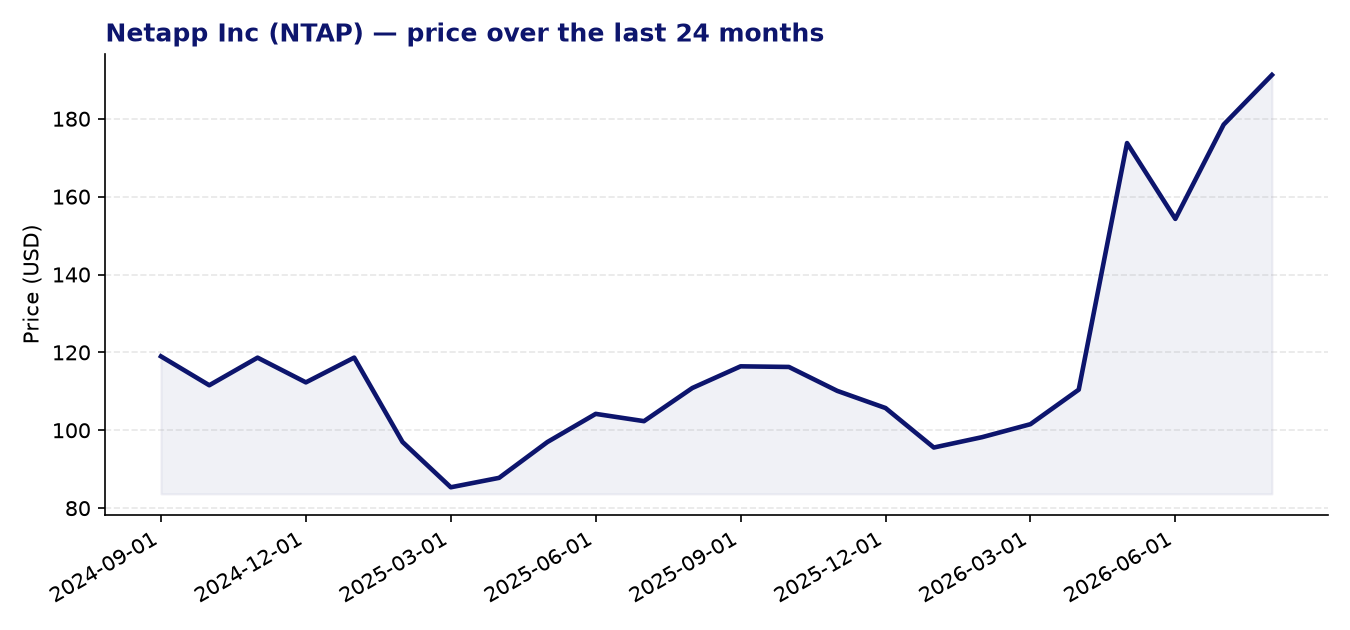
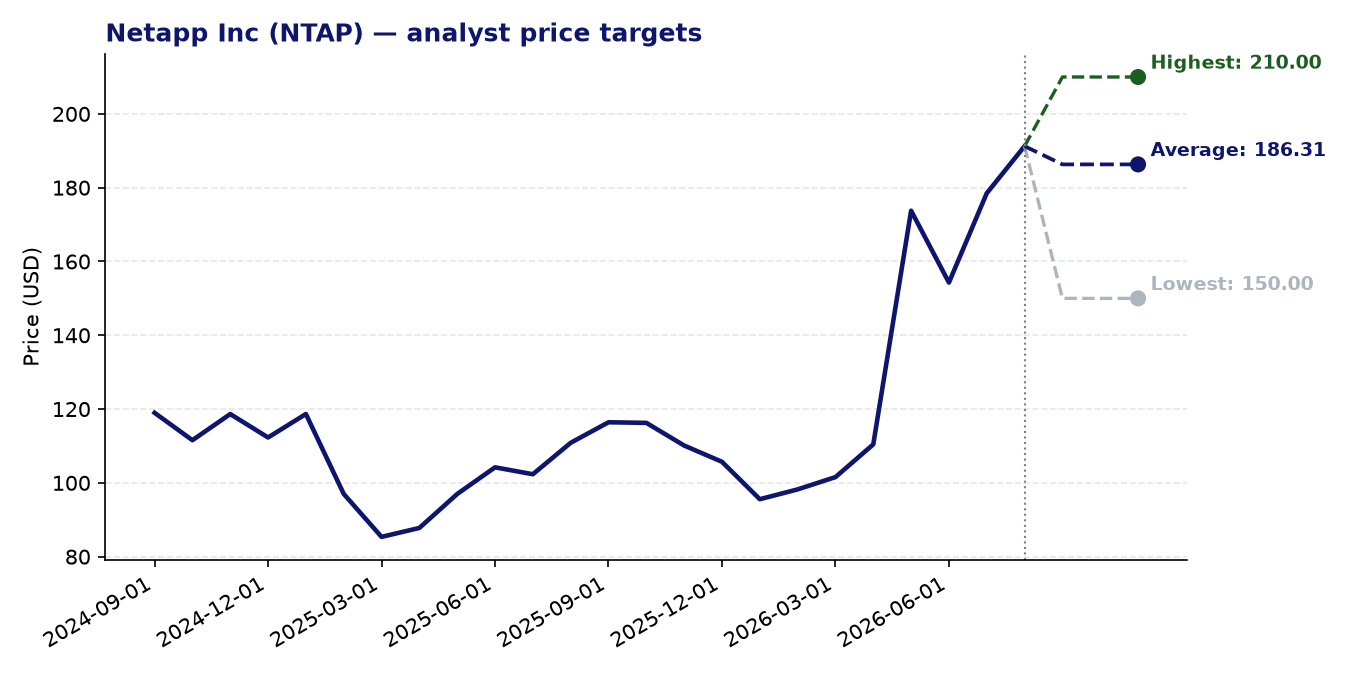
Netapp Inc (NTAP) — current price: 191.25 USD | average price target: 186.31 USD | potential: -2.6%
About Netapp Inc
- NetApp is a San Jose-based enterprise technology company founded in 1992, offering data management software, storage infrastructure solutions, and cloud storage services to customers across the Americas, EMEA, and Asia Pacific.
- Its two operating segments — Hybrid Cloud and Public Cloud — address the growing need for flexible, multi-environment data infrastructure, spanning on-premises systems and major cloud platforms including AWS, Microsoft Azure, and Google Cloud.
- Core software products such as ONTAP and its associated data replication, backup, and compliance tools form the backbone of NetApp’s recurring-revenue model.
- The company also provides professional and managed services, ransomware protection, disaster recovery, and storage-as-a-service (STaaS), serving sectors from financial services and healthcare to government and media.
- A strategic alliance with Commvault Systems strengthens its position in enterprise data protection and cyber resilience.
Recent news
- Citi raised its price target on NetApp to $209 ahead of the company’s Q1 FY2027 earnings report, pointing to AI-related customer wins and sustained growth in enterprise storage demand as key drivers.
- NetApp’s full-year fiscal 2025 results showed revenue of $6.57 billion, up 5% year-on-year, while non-GAAP EPS grew approximately 7.4% to $7.79, supported by a non-GAAP operating margin of 29.5%.
- Analysts at Zacks highlight that NetApp has a consistent track record of exceeding earnings expectations, a factor that may be relevant as the next quarterly report approaches.
- The stock declined around 5% in a single session in mid-August, notably underperforming a broadly positive market day, suggesting some near-term selling pressure independent of fundamental news.
Strengths
- NetApp’s 24-month momentum Z-score of 2.13 indicates meaningfully above-average price momentum relative to the broader market over the past two years.
- The forward P/E of 19.04 is considerably more modest than the trailing P/E of 30.12, implying the market anticipates solid earnings growth that could make the current valuation look less stretched in the near term.
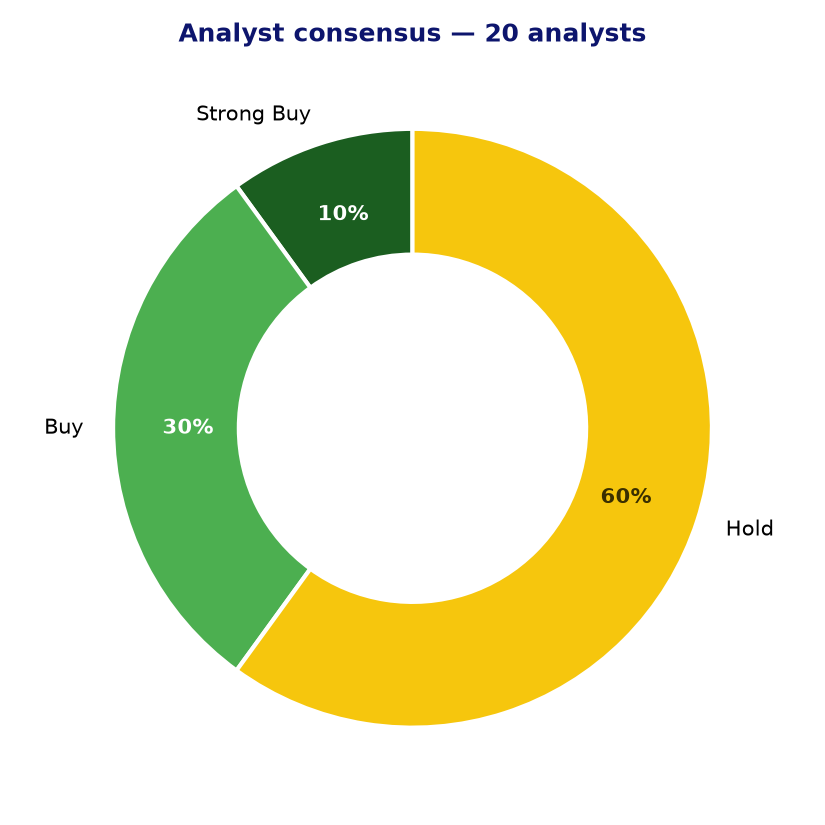
- Of 20 covering analysts, 8 rate the stock a buy or strong buy with none at sell, and Citi’s $209 target represents roughly 9% upside from current levels — suggesting selective but genuine institutional conviction.
- The company’s expanding footprint across all three major hyperscalers (AWS, Azure, Google Cloud) positions it well to capture ongoing enterprise migration to hybrid and multi-cloud architectures.
- A consistent history of earnings beats, combined with a healthy non-GAAP operating margin near 30%, points to disciplined cost management alongside revenue growth.
Points of attention and risks
- The average analyst price target of $186.31 sits roughly 2.6% below the current share price of $191.25, meaning the consensus view implies the stock is modestly overvalued at present levels.
- A PEG ratio of 2.16 suggests investors are paying a meaningful premium relative to the company’s earnings growth rate, which limits the margin of safety for new positions.
- Revenue growth of 5% for fiscal 2025, while steady, is relatively modest for a technology infrastructure company, and any deceleration could put pressure on a valuation that relies on continued earnings expansion.
- The stock’s sharp single-session decline of 5% in August — against a positive broader market — highlights that sentiment can shift quickly, and the wide target range ($150–$210) reflects genuine uncertainty among analysts about the near-term outlook.
- Enterprise storage is a competitive space, with NetApp facing ongoing pressure from pure-play flash storage vendors and cloud-native alternatives, which could constrain pricing power over time.
Analyst consensus and price targets
Conclusion
NetApp presents a reasonably well-managed infrastructure business with genuine exposure to secular trends in AI-driven storage demand and hybrid cloud adoption, supported by solid margins and a consistent earnings track record. However, the stock is currently trading slightly above the analyst consensus price target, and the PEG ratio suggests growth expectations are already priced in to a meaningful degree. Investors would do well to weigh the company’s durable competitive position and momentum against a valuation that leaves limited room for disappointment, particularly given the competitive dynamics of the enterprise storage market.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 26-08-2026. Not investment advice.