
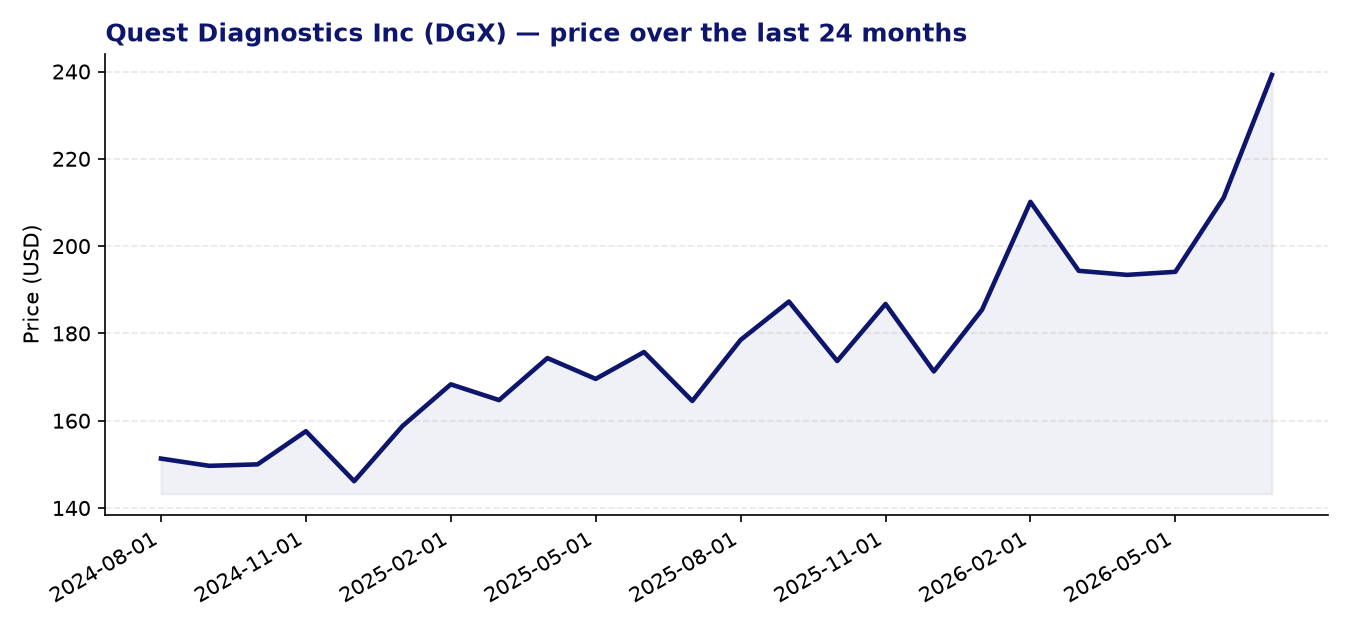
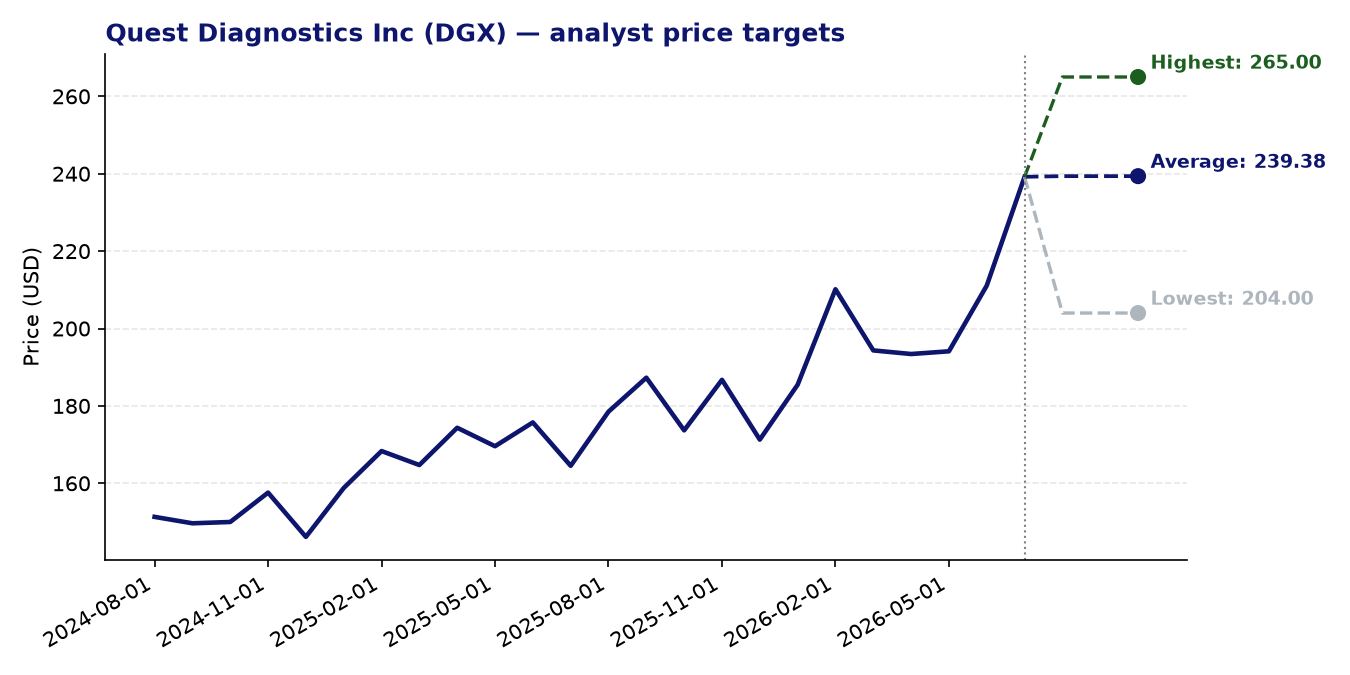
Quest Diagnostics Inc (DGX) — current price: 239.21 USD | average price target: 239.38 USD | potential: +0.1%
About Quest Diagnostics Inc
- Quest Diagnostics is one of the largest clinical laboratory networks in the United States, providing routine and advanced diagnostic testing services to a broad range of clients including physicians, hospitals, health plans, employers, and government agencies.
- The company operates under several brand names — including AmeriPath, Dermpath Diagnostics, ExamOne, and Quanum — and delivers services through an extensive network of laboratories, patient service centres, and mobile phlebotomists.
- Its test menu spans a wide range of specialties, including cardiometabolic, oncology, infectious disease, neurology (including Alzheimer’s diagnostics), women’s health, and workplace drug testing.
- Quest also provides value-added services such as life insurance risk assessment, healthcare IT connectivity solutions, population health management, and employer wellness programmes.
- Founded in 1967 and headquartered in Secaucus, New Jersey, the company has a market capitalisation of approximately $23.5 billion.
Recent news
- Quest Diagnostics released its second-quarter 2026 earnings results in late July, with a conference call transcript made available through financial media — suggesting the market has had the opportunity to digest recent performance figures.
- Earlier in 2026, the stock reached a new 52-week high of around $216.87, reflecting a double-digit gain over a one-month period at the time — the shares have since moved higher still to current levels near $239.
- Multiple financial research platforms, including Zacks, have highlighted Quest Diagnostics as a notable momentum stock in mid-2026, pointing to its sustained upward price trend as a factor of interest for momentum-oriented investors.
- No significant product launches, acquisitions, or regulatory developments were reported in the search results for this period beyond the earnings release and momentum commentary.
Strengths
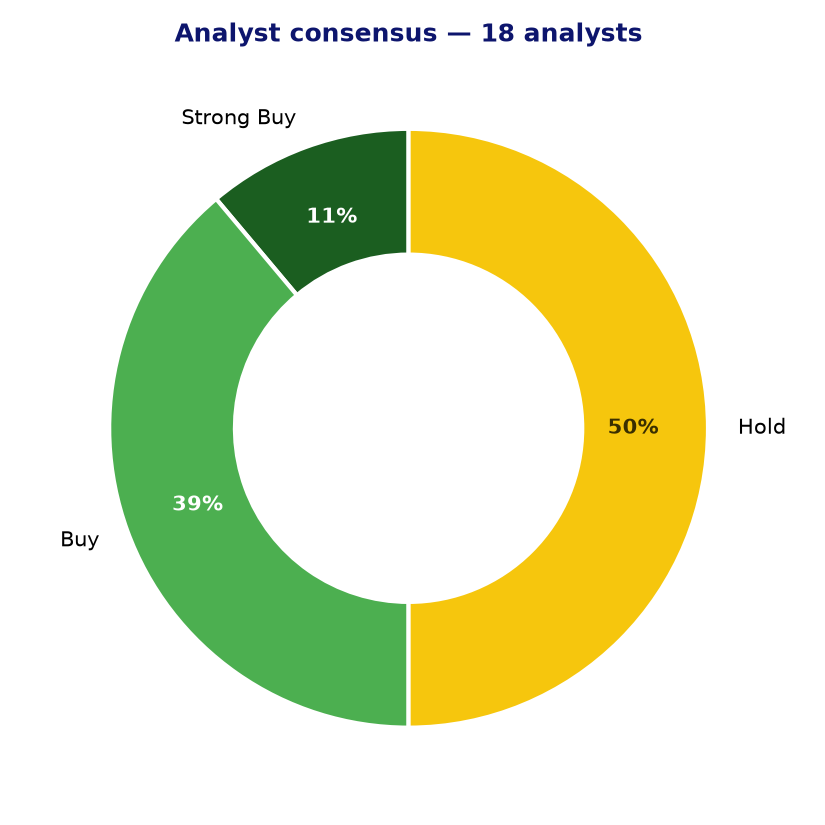
- Analyst sentiment is broadly constructive, with 9 out of 18 covering analysts rating the stock a buy or strong buy and none carrying a sell rating, indicating a relatively clean consensus view.
- The stock’s 24-month Z-score momentum of 2.57 is a meaningful signal of sustained price strength relative to its own history, suggesting the market has been consistently re-rating the shares upward.
- The forward P/E of approximately 20x represents a notable discount to the trailing P/E of 25x, implying that earnings are expected to grow meaningfully in the near term and that the valuation may become more attractive as those earnings materialise.
- Quest operates in a structurally resilient sector — diagnostic testing demand is largely non-discretionary and benefits from an ageing US population, expanding chronic disease prevalence, and ongoing healthcare digitisation trends.
- The company’s diversified revenue base — spanning clinical labs, employer wellness, life insurance risk assessment, and healthcare IT — provides some insulation against weakness in any single end market.
Points of attention and risks
- The average analyst price target of $239.38 sits virtually at the current share price, implying that consensus estimates leave almost no upside at present levels and that much of the positive outlook may already be priced in.
- The PEG ratio of 1.75, while not extreme, suggests the stock is not obviously cheap relative to its near-term earnings growth rate, limiting the margin of safety for new investors.
- EPS growth of 0.14 (14%) is modest for a stock trading at these multiples, and any disappointment in the pace of earnings recovery could weigh on the valuation.
- The diagnostics sector faces ongoing reimbursement pressure from government and commercial payers, and any adverse changes to Medicare or Medicaid fee schedules could impact Quest’s revenue per test.
- The wide spread between the lowest ($204) and highest ($265) analyst price targets reflects genuine disagreement about the stock’s fair value, highlighting meaningful uncertainty around the growth and margin outlook.
Analyst consensus and price targets
Conclusion
Quest Diagnostics presents a stable, well-established business with a broad service offering and resilient demand characteristics, supported by broadly positive analyst sentiment and strong price momentum over the past two years. However, with the consensus price target essentially in line with the current share price, the stock appears to be fairly valued at present, leaving limited room for error if near-term earnings disappoint or if reimbursement conditions tighten. Investors who already hold the stock may find the fundamental backdrop reassuring, while those considering a new position may wish to assess whether the current valuation adequately reflects the risks alongside the opportunities.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 28-07-2026. Not investment advice.