
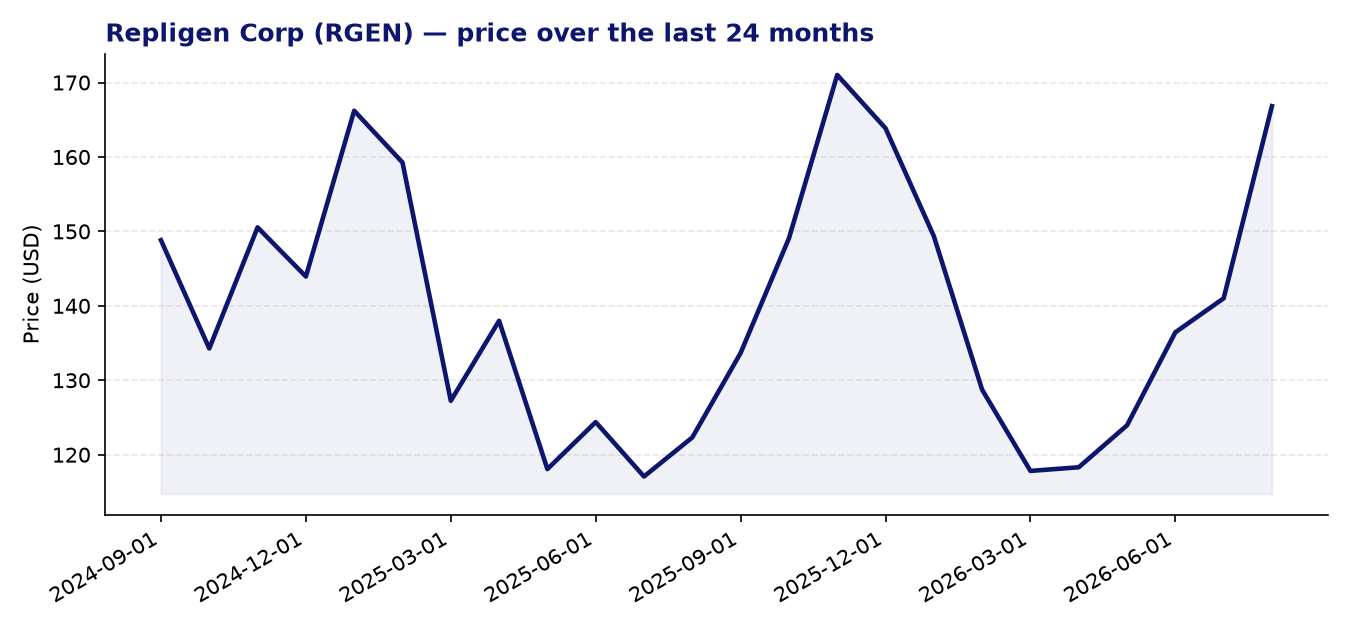
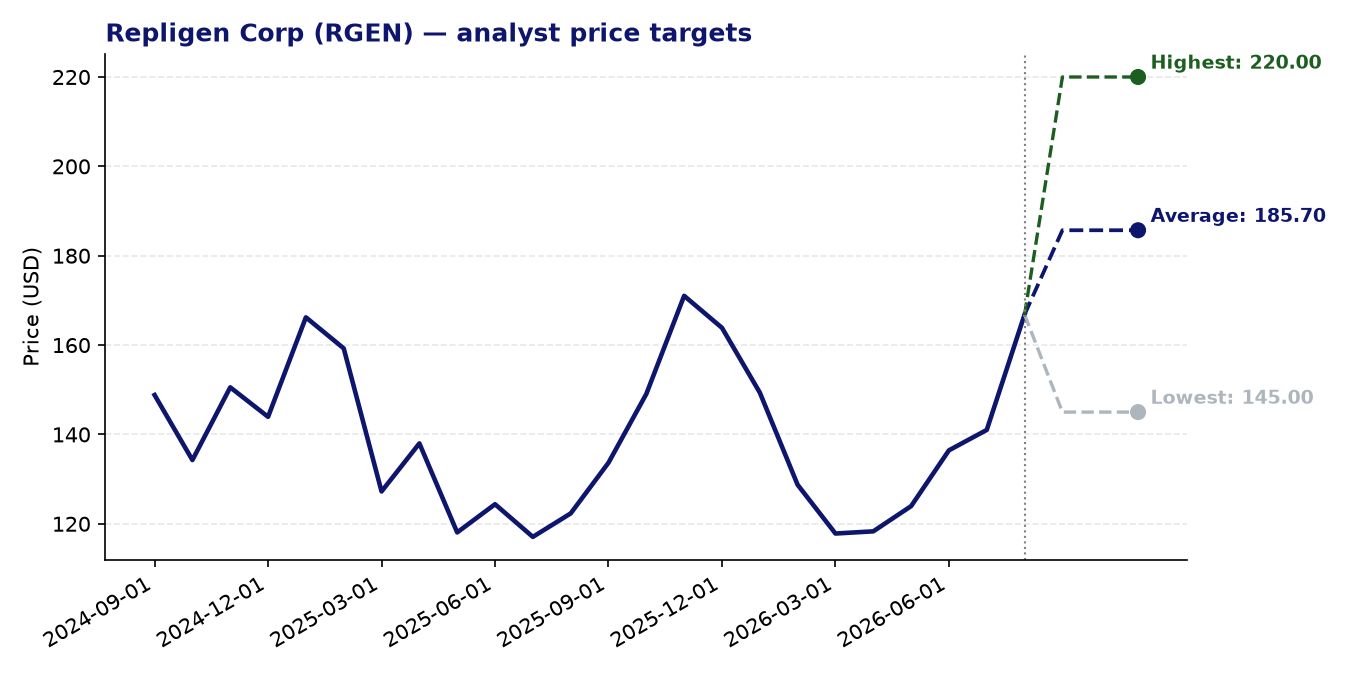
Repligen Corp (RGEN) — current price: 166.83 USD | average price target: 185.70 USD | potential: +11.3%
About Repligen Corp
- Repligen Corporation develops and commercialises bioprocessing technologies used in the manufacturing of biological drugs, serving biopharmaceutical companies, contract manufacturing organisations, and laboratory researchers worldwide.
- Its product portfolio spans filtration systems, chromatography columns and resins, process analytics instruments, and cell culture tools sold under a range of established brand names including OPUS, XCell ATF, KrosFlo, and SoloVPE.
- The company operates across North America, Europe, and the Asia Pacific, with products used at multiple stages of the biologic drug production process, from upstream cell culture to downstream purification and formulation.
- Repligen collaborates with Navigo Proteins GmbH to develop affinity ligands, reflecting its focus on expanding its proprietary technology base in bioprocessing.
Recent news
- Repligen reported second-quarter 2026 adjusted earnings per share of $0.54, substantially ahead of the consensus analyst estimate of $0.45 and well above the $0.37 recorded in the same period a year earlier.
- Following the earnings beat, management raised its full-year 2026 financial guidance, signalling growing confidence in the company’s near-term trajectory.
- The market responded strongly to these results, with shares gaining roughly 14–16% on the day of the announcement, recovering meaningful ground from prior levels.
Strengths
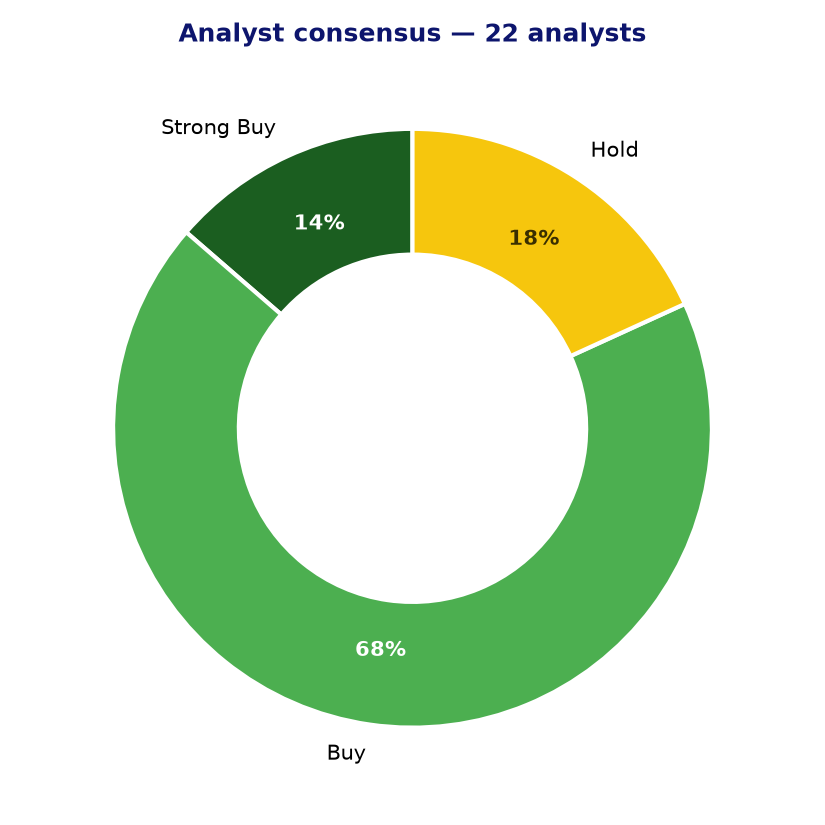
- Analyst sentiment is broadly constructive: 18 of 22 covering analysts hold a buy or strong buy rating, with the average price target of $185.70 implying approximately 11% upside from the current price of $166.83.
- The 24-month momentum Z-score of 2.10 indicates that the stock has been trending meaningfully above its historical average, suggesting sustained positive price momentum.
- The Q2 2026 earnings beat was substantial — adjusted EPS came in roughly 20% ahead of consensus — and the accompanying guidance upgrade suggests the operational recovery is gathering pace.
- Repligen’s diversified portfolio of consumables, instruments, and analytics products provides exposure across multiple stages of biologic drug manufacturing, which can support recurring revenue streams.
- The highest analyst price target stands at $220, indicating that a portion of the analyst community sees considerably more upside if the recovery in bioprocessing demand accelerates further.
Points of attention and risks
- Valuation remains a point of attention: a trailing P/E of 225x and a forward P/E of 63x imply that the market is pricing in a significant and sustained earnings recovery, leaving limited margin for disappointment.
- The PEG ratio of 2.17 suggests the stock is not cheap relative to its near-term growth profile, and the trailing EPS growth figure is currently negative, reflecting the industry-wide bioprocessing demand slowdown of recent years.
- The bioprocessing sector has experienced inventory destocking among biopharmaceutical customers, and while conditions appear to be improving, the pace and durability of the recovery remain uncertain.
- The wide spread between the lowest ($145) and highest ($220) analyst price targets reflects genuine uncertainty about the company’s earnings trajectory, with the downside target sitting below the current price.
- As a predominantly consumables- and instruments-focused business, Repligen’s revenue is sensitive to capital spending and inventory decisions by biopharmaceutical customers, which can shift rapidly with industry sentiment.
Analyst consensus and price targets
Conclusion
Repligen’s strong Q2 2026 results and raised guidance represent an encouraging step in what has been a challenging recovery period for the bioprocessing sector, and the broadly positive analyst consensus reflects confidence in the company’s product portfolio and market position. However, the stock’s elevated valuation multiples mean that continued execution will need to be consistent and visible to justify the current price, and investors should weigh the recovery narrative carefully against the sector’s history of demand volatility. The momentum indicators are supportive, but the gap between the trailing earnings picture and the growth implied by the forward multiple warrants a measured assessment of risk.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 14-08-2026. Not investment advice.