
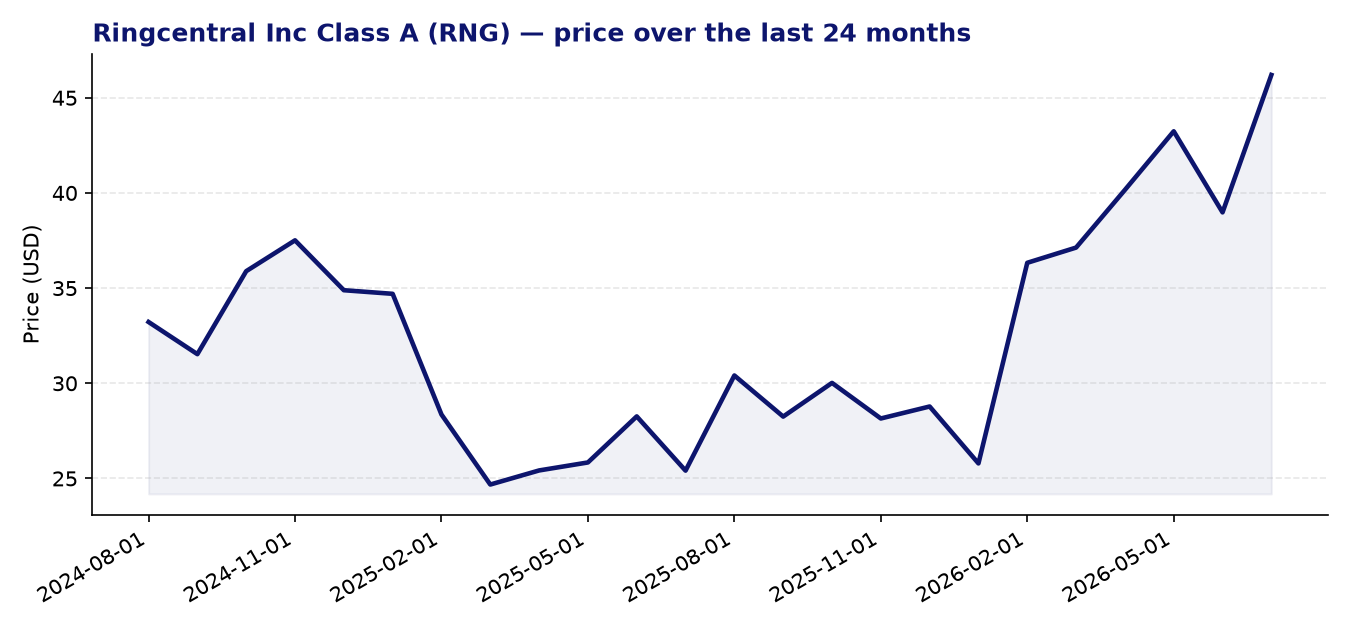
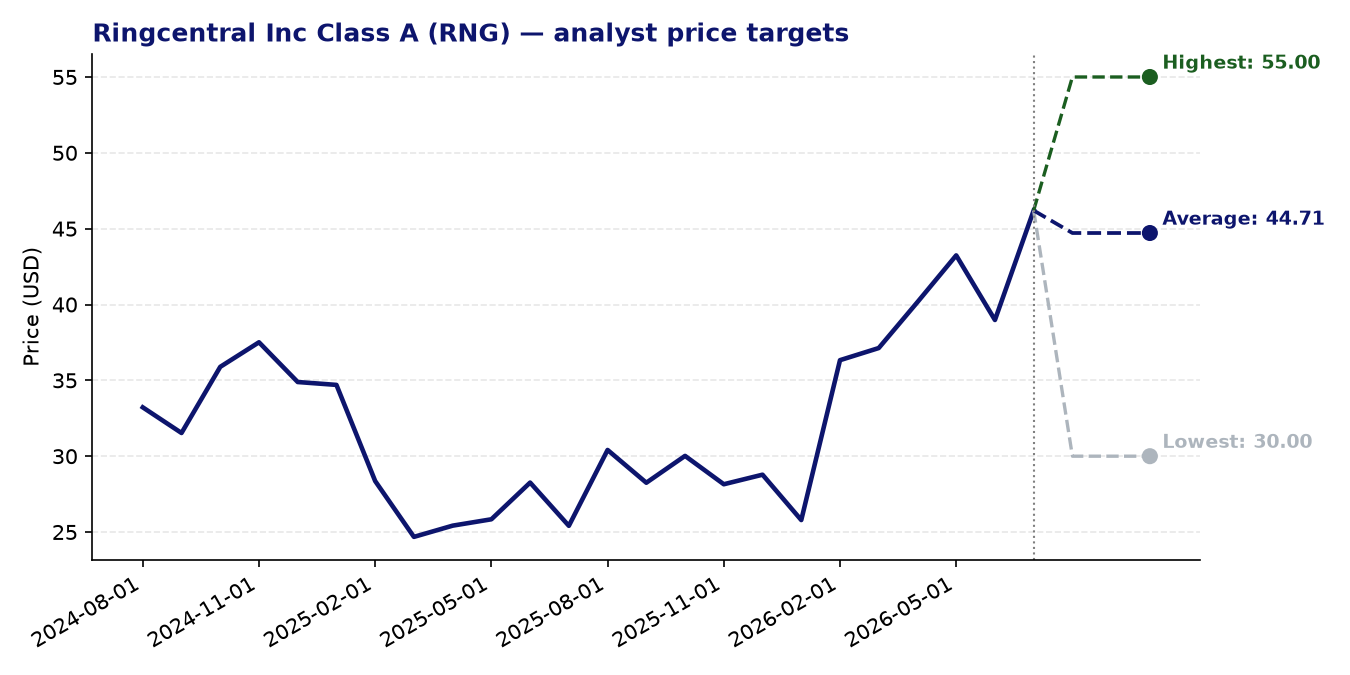
Ringcentral Inc Class A (RNG) — current price: 46.20 USD | average price target: 44.71 USD | potential: -3.2%
About Ringcentral Inc Class A
- RingCentral is a cloud-based business communications platform founded in 1999 and headquartered in Belmont, California, offering unified communications, contact centre, and video collaboration solutions under brands including RingEX and RingCX.
- The company has embedded artificial intelligence across its product suite, with tools such as AI Receptionist, AI Agent Assist, and AI-based Quality Management designed to automate and enhance business communication workflows.
- RingCentral serves a broad range of industries — from healthcare and financial services to government and education — selling to both enterprise clients and small-to-medium businesses via direct and indirect channels including resellers, distributors, and global service providers.
- Its contact centre offerings integrate CRM systems and provide omni-channel customer engagement, workforce engagement management, and real-time supervisor and agent support powered by AI.
Recent news
- RingCentral reported Q2 earnings and provided forward guidance, indicating expected Q3 revenue of $664–670 million and per-share earnings of $1.25–$1.30 for the September quarter.
- Multiple financial research outlets highlighted RingCentral as a noteworthy value and growth stock in mid-2026, reflecting renewed interest in the shares following a period of relative underperformance.
- The stock dipped in mid-June alongside broader market softness after the Federal Reserve opted to hold its benchmark interest rate steady in the 3.5–3.75% range, a decision that weighed on some technology names.
Strengths
- The forward P/E of 8.5x is notably low for a software-as-a-service business, suggesting the market may be underpricing the company’s earnings power on a near-term basis.
- A PEG ratio of 0.21 indicates that earnings growth is running well ahead of the current valuation multiple, which is typically considered a favourable signal for value-oriented investors.
- The 24-month Z-score momentum reading of 2.31 reflects meaningful positive price momentum relative to the stock’s own history, suggesting improving market sentiment.
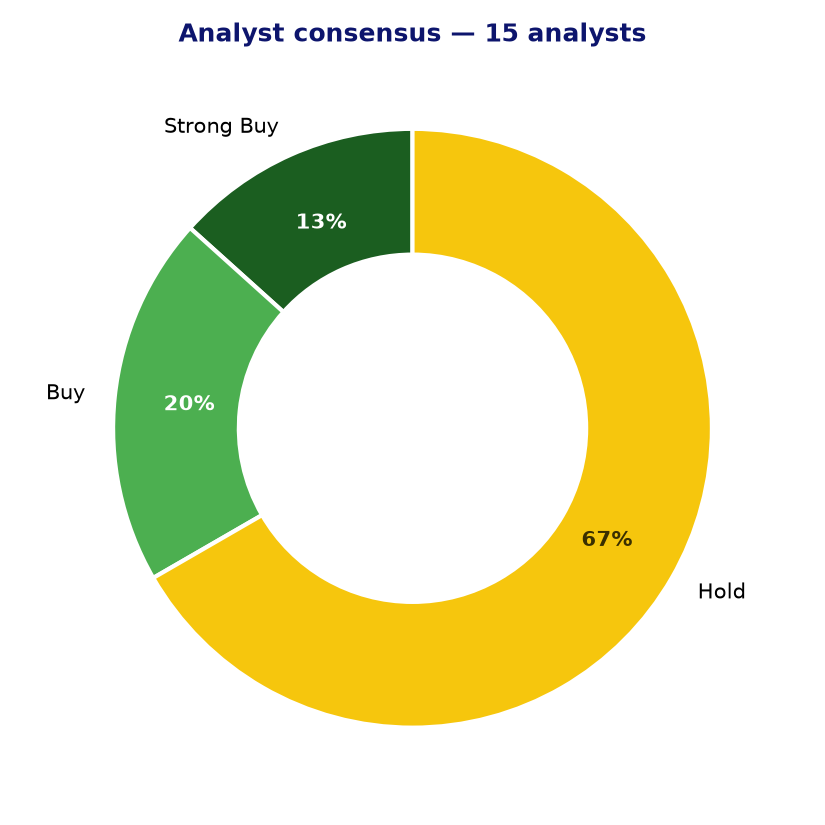
- The analyst community leans constructive, with five of fifteen covering analysts rating the stock a buy or strong buy and no sell ratings registered across the panel.
- RingCentral’s deepening AI integration — spanning reception, quality management, and real-time agent assistance — positions it competitively in the fast-growing agentic AI and contact centre market.
Points of attention and risks
- The average analyst price target of $44.71 sits approximately 3.2% below the current share price of $46.20, suggesting the stock may have moved ahead of consensus near-term expectations.
- Ten of fifteen analysts hold a neutral stance, indicating that conviction among the covering community is limited despite the attractive valuation ratios.
- The trailing P/E of 49.15x is considerably higher than the forward multiple, pointing to historically uneven earnings delivery and the need for continued execution to justify current pricing.
- The cloud communications sector is intensely competitive, with Microsoft Teams, Zoom, and Cisco Webex all vying for similar enterprise customers, which can pressure both pricing and retention rates.
- EPS growth of 1.97 (as a multiple) implies strong projected expansion, but software companies with ambitious growth assumptions carry execution risk, particularly if enterprise IT spending moderates.
Analyst consensus and price targets
Conclusion
RingCentral presents an interesting mix of an undemanding forward valuation and a credible AI-driven product roadmap, at a time when contact centre and unified communications demand remains structurally supported. However, the stock is trading modestly above the analyst consensus price target, and the majority of covering analysts currently sit on the sidelines, suggesting that much of the near-term optimism may already be reflected in the price. Investors willing to take a longer-term view on the company’s AI integration and revenue stability may find the risk-reward profile worth monitoring, though the competitive intensity of the sector and the gap between trailing and forward earnings multiples warrant careful scrutiny.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 24-07-2026. Not investment advice.