
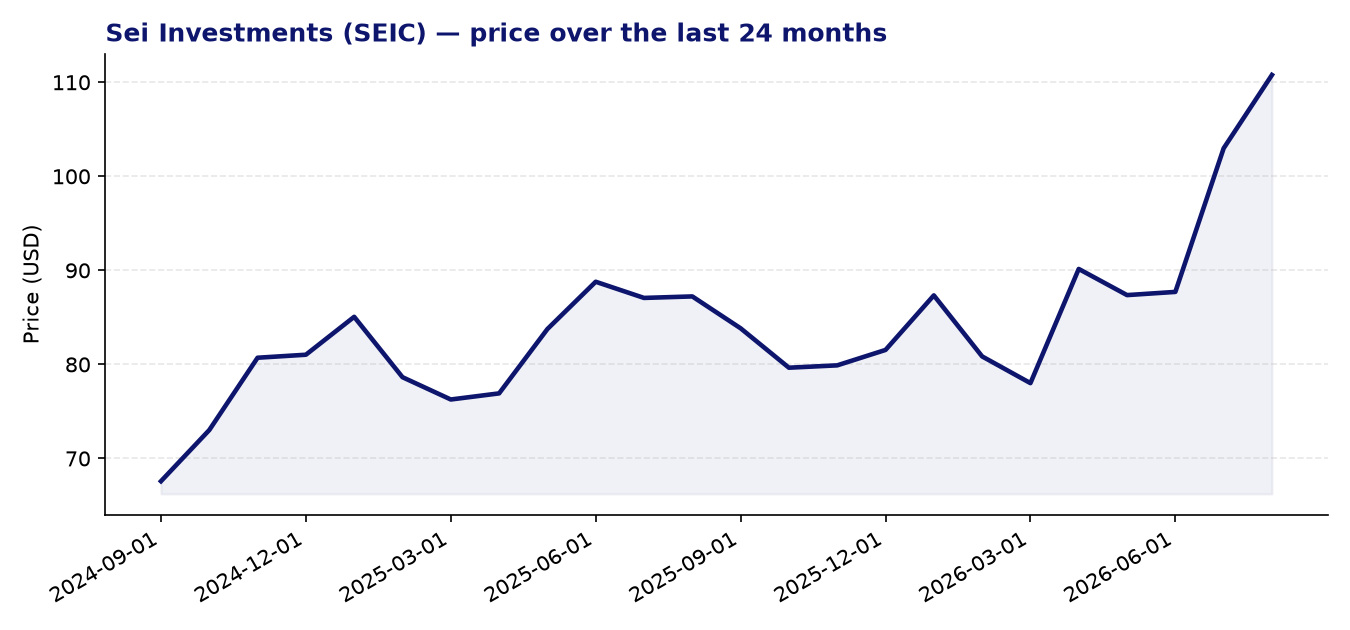
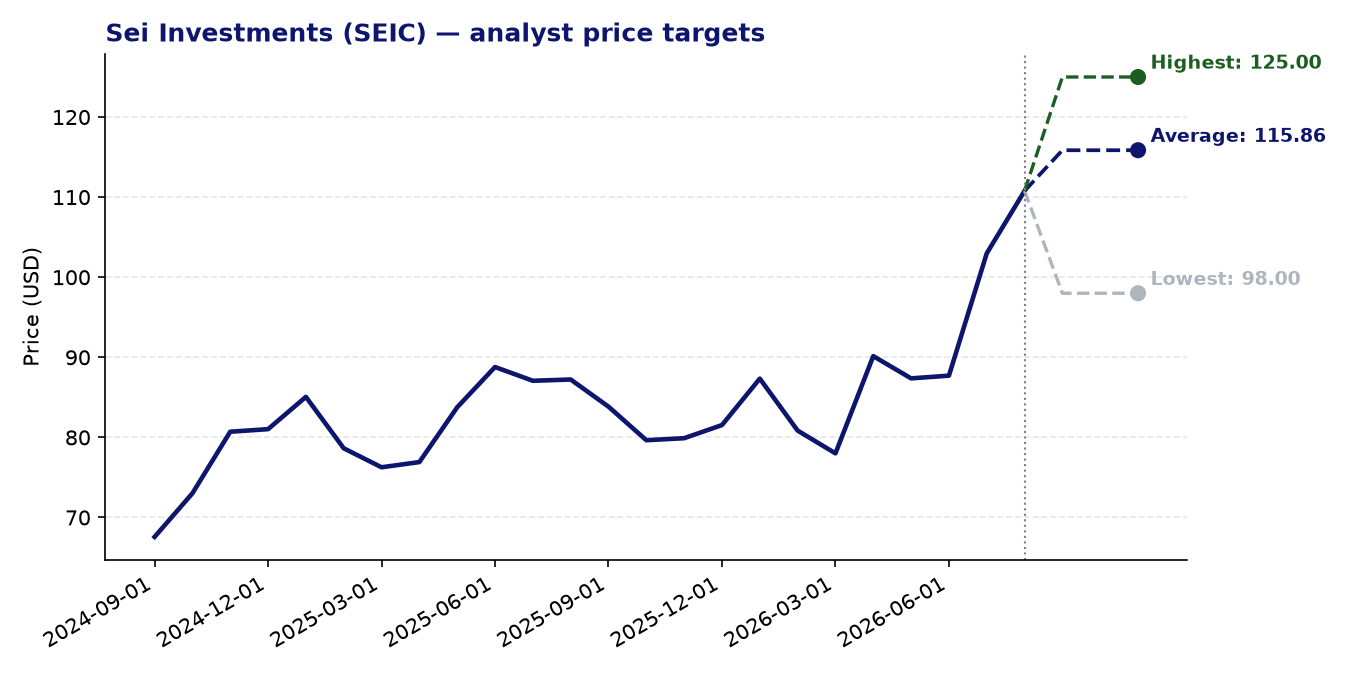
Sei Investments (SEIC) — current price: 110.78 USD | average price target: 115.86 USD | potential: +4.6%
About Sei Investments
- SEI Investments Company, founded in 1968 and headquartered in Oaks, Pennsylvania, is a diversified asset management holding company serving clients across North America, Europe, Asia, and Africa.
- The firm delivers wealth management, investment processing outsourcing, asset administration, and investment advisory services to a broad client base that includes private banks, institutional investors, registered investment advisers, and retirement scheme sponsors.
- Through its subsidiaries, SEI manages separate client portfolios and runs equity, fixed income, and balanced mutual funds, investing in public markets using both fundamental and quantitative analysis.
- The company’s technology-driven outsourcing solutions for investment managers and financial intermediaries form a distinctive part of its business model, differentiating it from pure-play asset managers.
Recent news
- SEI reported Q2 2026 adjusted earnings of $1.66 per share, surpassing the consensus analyst estimate of $1.45 per share by approximately 15.5%, though the result was below the $1.78 per share earned in the same quarter a year ago.
- Operating margins expanded sharply in the quarter, rising around 500 basis points to reach 32%, reflecting improved operational efficiency and revenue growth that management described as record-level.
- Encouraged by the strong quarterly performance, SEI’s management indicated it is accelerating its share buyback programme, having already deployed $112 million in repurchases during Q2 2026.
- A broader review of custody and asset-servicing bank stocks for Q2 identified SEI as among the stronger performers within its peer group for the period.
Strengths
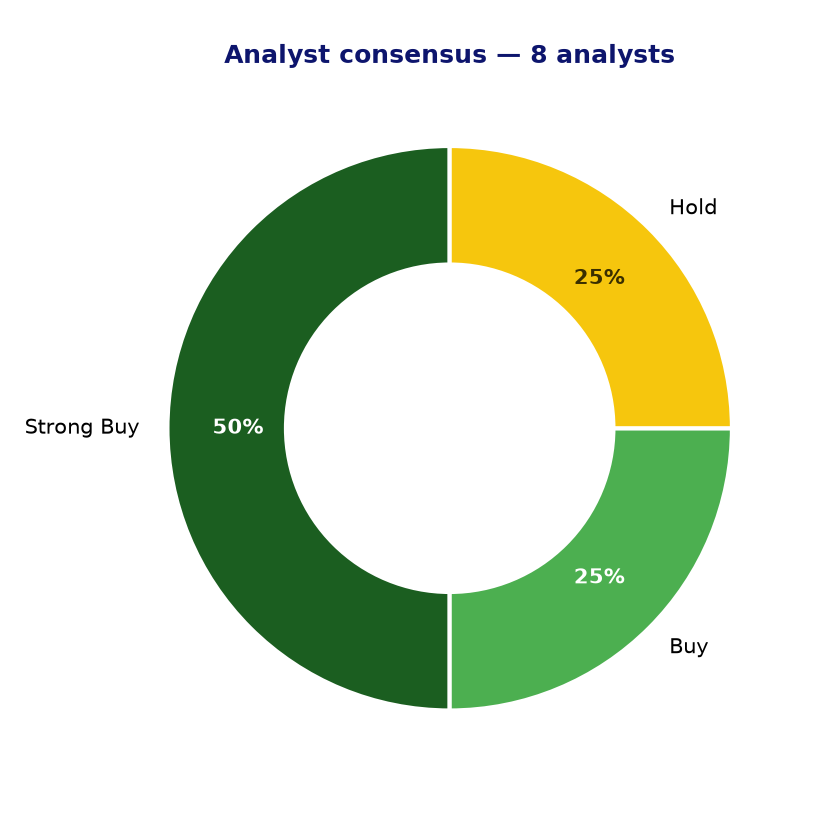
- Analyst sentiment is broadly constructive: six of eight covering analysts rate the stock a buy or strong buy, with half assigning their strongest positive rating, and no sell recommendations on record.
- The consensus price target of $115.86 implies modest but meaningful upside of around 4.6% from the current price, with the most optimistic target reaching $125.00.
- A 24-month Z-score momentum reading of 2.10 suggests the stock has maintained above-average price momentum relative to its history, a positive technical signal for trend-oriented investors.
- The forward P/E of 16.0x is noticeably lower than the trailing P/E of 19.5x, indicating that earnings are expected to grow, and the valuation appears less stretched on a forward-looking basis.
- SEI’s diversified revenue mix—spanning software-driven processing, asset management, and advisory services—provides some resilience against swings in any single business line or market segment.
Points of attention and risks
- Trailing EPS growth is currently slightly negative (-0.14%), and while the Q2 2026 beat was significant relative to estimates, adjusted earnings per share were still below the comparable quarter from the prior year, pointing to a period of earnings pressure.
- A PEG ratio of 2.11 suggests the stock is not obviously cheap relative to its growth rate; investors are paying a meaningful premium for anticipated earnings expansion that has yet to fully materialise.
- The consensus price target upside of just 4.6% is relatively narrow, leaving limited margin of safety if earnings recovery takes longer than the market currently expects or if macroeconomic conditions deteriorate.
- SEI operates in a competitive and fee-sensitive industry: ongoing margin pressure from passive investment products, fee compression, and technology disruption remain structural headwinds for traditional asset managers and outsourcing providers.
- The wide range between the lowest ($98.00) and highest ($125.00) analyst price targets reflects genuine uncertainty about the pace and durability of SEI’s earnings recovery, which investors should weigh carefully.
Analyst consensus and price targets
Conclusion
SEI Investments enters the second half of 2026 with a solid operational beat behind it, improving margins, and a broadly supportive analyst community, all of which lend credibility to its ongoing recovery narrative. That said, the combination of a modest near-term price-target upside, a PEG ratio above two, and year-on-year EPS still in slight decline suggests the recovery story is not yet fully validated. Investors with a longer time horizon may find the diversified business model and accelerating buybacks attractive, but the current valuation leaves little room for disappointment should revenue growth or margin expansion prove slower than anticipated.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 26-08-2026. Not investment advice.