
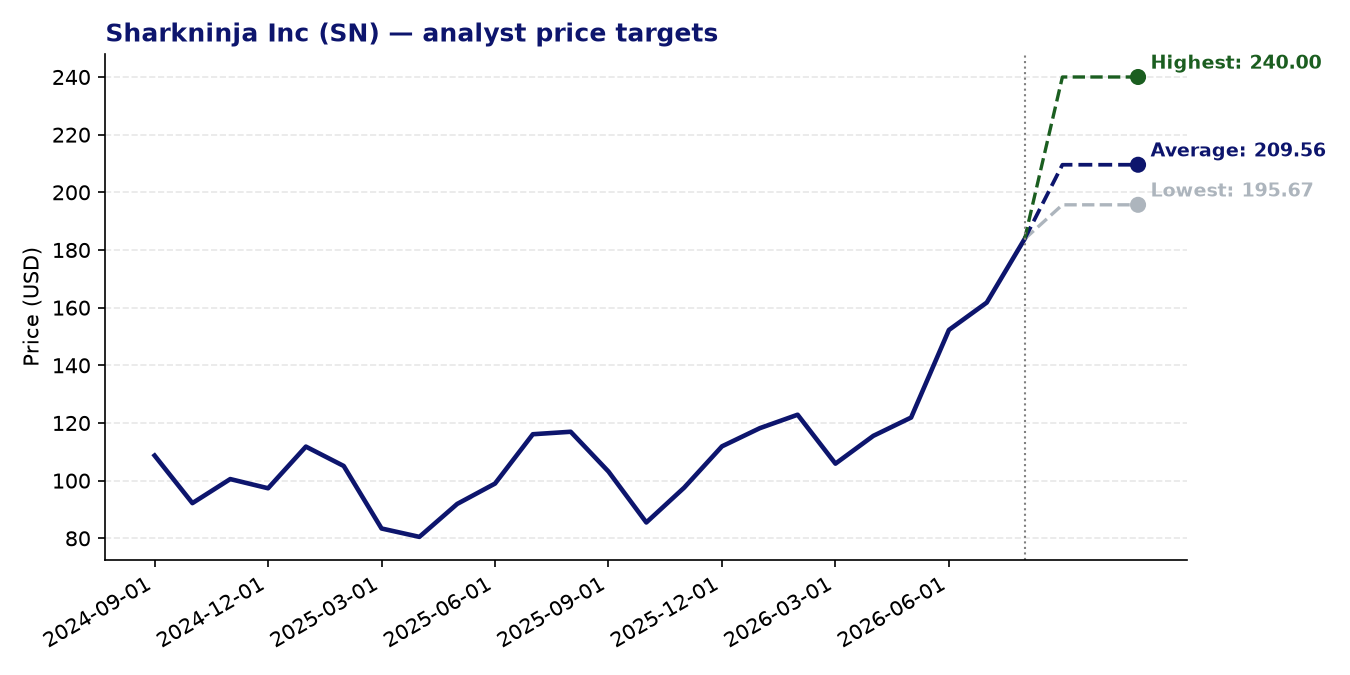
Sharkninja Inc (SN) — current price: 183.80 USD | average price target: 209.56 USD | potential: +14.0%
About Sharkninja Inc
- SharkNinja designs and sells a broad range of consumer appliances under its Shark and Ninja brands, spanning cleaning, cooking, food preparation, beauty, and home environment categories.
- The company distributes its products through brick-and-mortar retail, e-commerce, and direct-to-consumer channels in the United States, China, and international markets.
- Its two flagship brands occupy distinct niches: Shark is primarily associated with floorcare and cleaning products, while Ninja covers kitchen appliances, cookware, and beverage systems.
- Headquartered in Needham, Massachusetts, SharkNinja has grown steadily since its incorporation in 2017 into a global consumer products business with a strong innovation-driven identity.
Recent news
- SharkNinja delivered its 13th consecutive quarter of double-digit net sales growth in Q2 2026, with revenues rising 22.2% year-over-year to $1.77 billion and adjusted earnings per share climbing nearly 30%.
- The company posted what analysts described as an earnings triple play — beating both EPS and sales estimates while simultaneously raising full-year guidance, which now calls for 16–17% net sales growth and adjusted EPS of $6.45–$6.55.
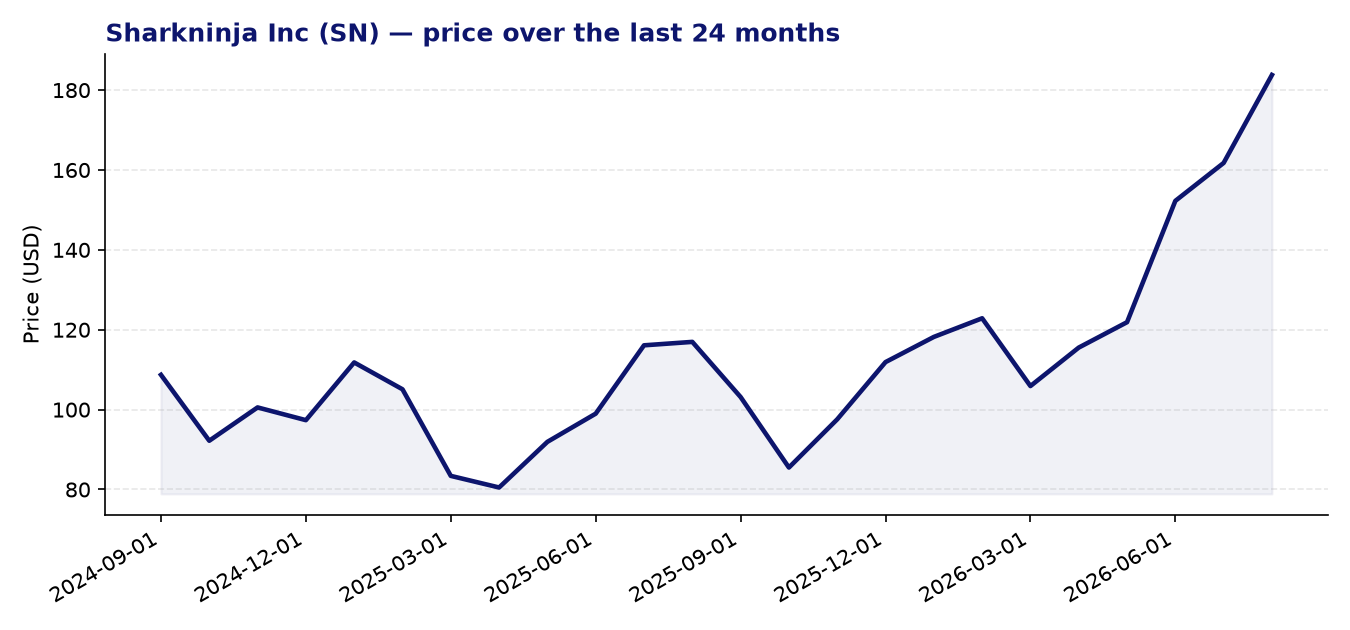
- SharkNinja shares hit a new 52-week high of $191.22 in mid-August, with the stock gaining approximately 25% over the preceding month, reflecting the positive market reaction to strong results.
- Ahead of the Q2 report, analysts were already noting SharkNinja’s consistent track record of surpassing earnings expectations, a streak that the company has now extended further.
Strengths
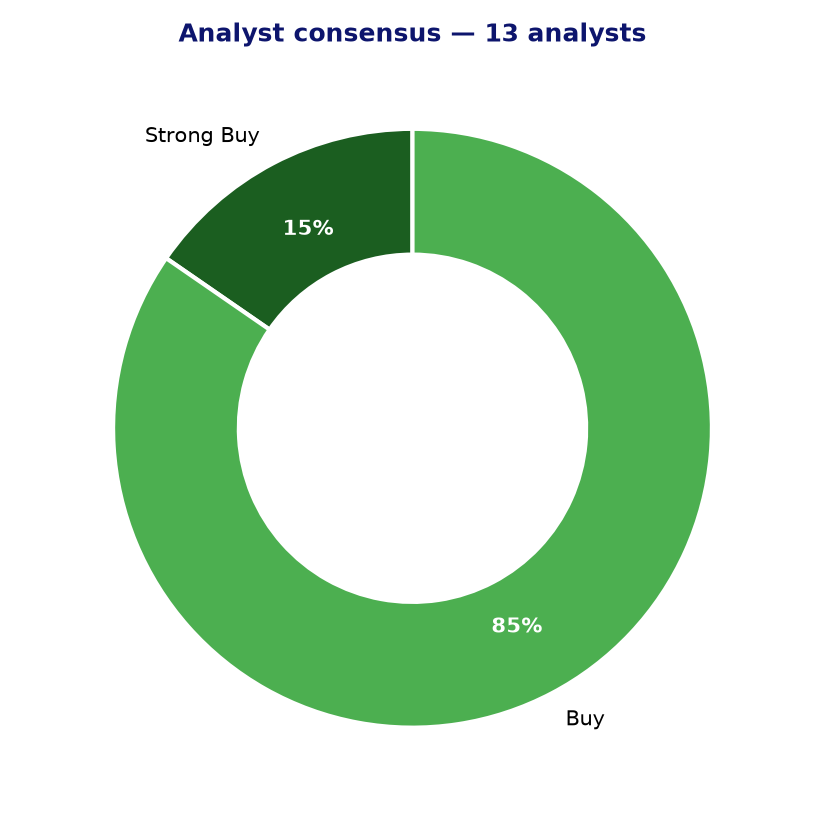
- Analyst sentiment is uniformly constructive, with 13 covering analysts rating the stock either buy or strong buy and no hold or sell ratings on record.
- The consensus price target of $209.56 implies approximately 14% upside from the current price of $183.80, with the most optimistic target reaching $240.00.
- A 24-month Z-score momentum reading of 2.21 indicates that the stock has been exhibiting meaningfully above-average price momentum relative to its own history, a signal that can reflect sustained investor confidence.
- The company has not missed an earnings or sales estimate in any reported quarter, and has raised guidance in roughly half of its quarterly reports — a rare consistency in the consumer appliances space.
- The forward P/E of 24.0 is considerably more modest than the trailing P/E of 37.5, suggesting that earnings growth is expected to close the valuation gap relatively quickly if management guidance proves accurate.
Points of attention and risks
- The trailing P/E of 37.5 is elevated for a consumer cyclical business, and the PEG ratio of 2.81 suggests the market is pricing in a sustained high growth rate that leaves little room for disappointment.
- Trailing EPS growth is currently reported at essentially flat (-0.07), meaning the premium valuation rests heavily on forward expectations rather than demonstrated recent earnings expansion.
- As a consumer cyclical company, SharkNinja is exposed to shifts in household spending, and any softening in consumer confidence or disposable income could weigh on demand for discretionary appliances.
- The stock’s sharp 25% gain over a single month means some near-term positive news may already be reflected in the price, and the current price of $183.80 sits near the low end of the analyst target range at $195.67.
- International expansion, particularly in China, introduces currency, regulatory, and geopolitical risks that are difficult to fully anticipate and could affect reported results.
Analyst consensus and price targets
Conclusion
SharkNinja presents a compelling operational track record, with consistent double-digit revenue growth, an unblemished record of meeting or beating estimates, and unanimous bullish analyst coverage pointing to meaningful upside from current levels. However, the valuation is not undemanding — a trailing P/E above 37 and a PEG ratio of 2.81 mean the stock is priced for continued execution, and any stumble in growth or consumer spending could prove costly for the share price. Investors who already hold a position may find the momentum and raised guidance reassuring, while those considering entry may wish to weigh the stretched near-term valuation and the stock’s recent sharp run-up carefully.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 25-08-2026. Not investment advice.