
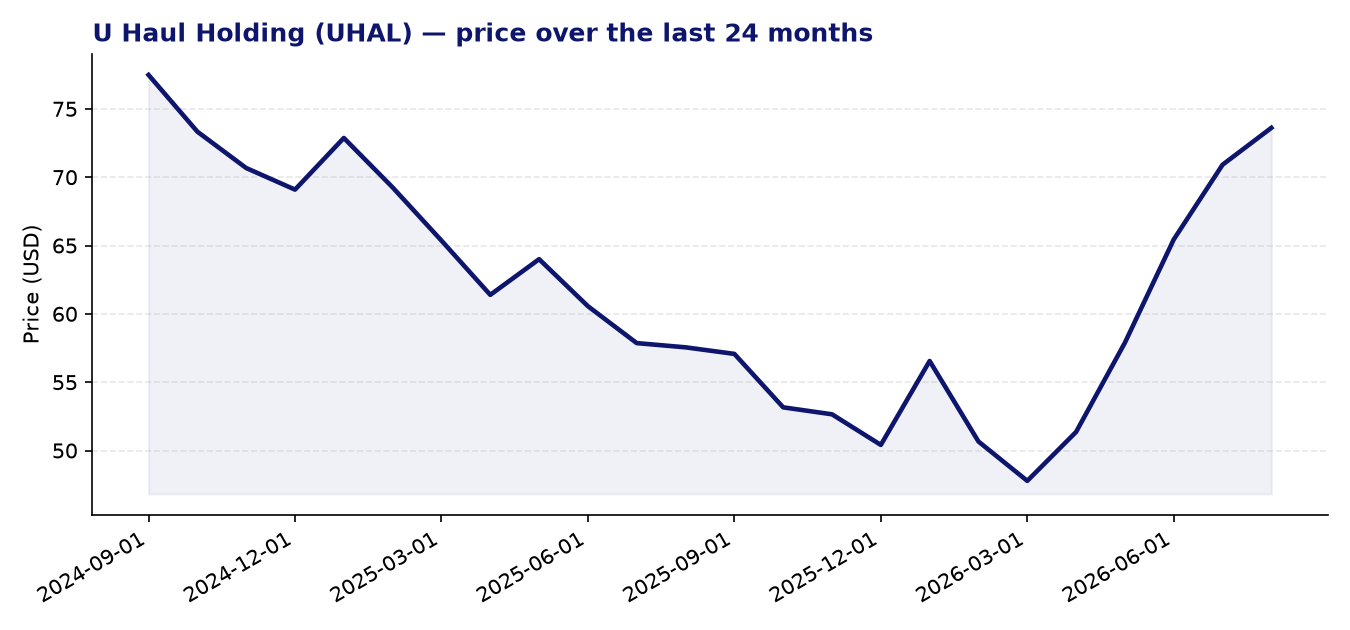
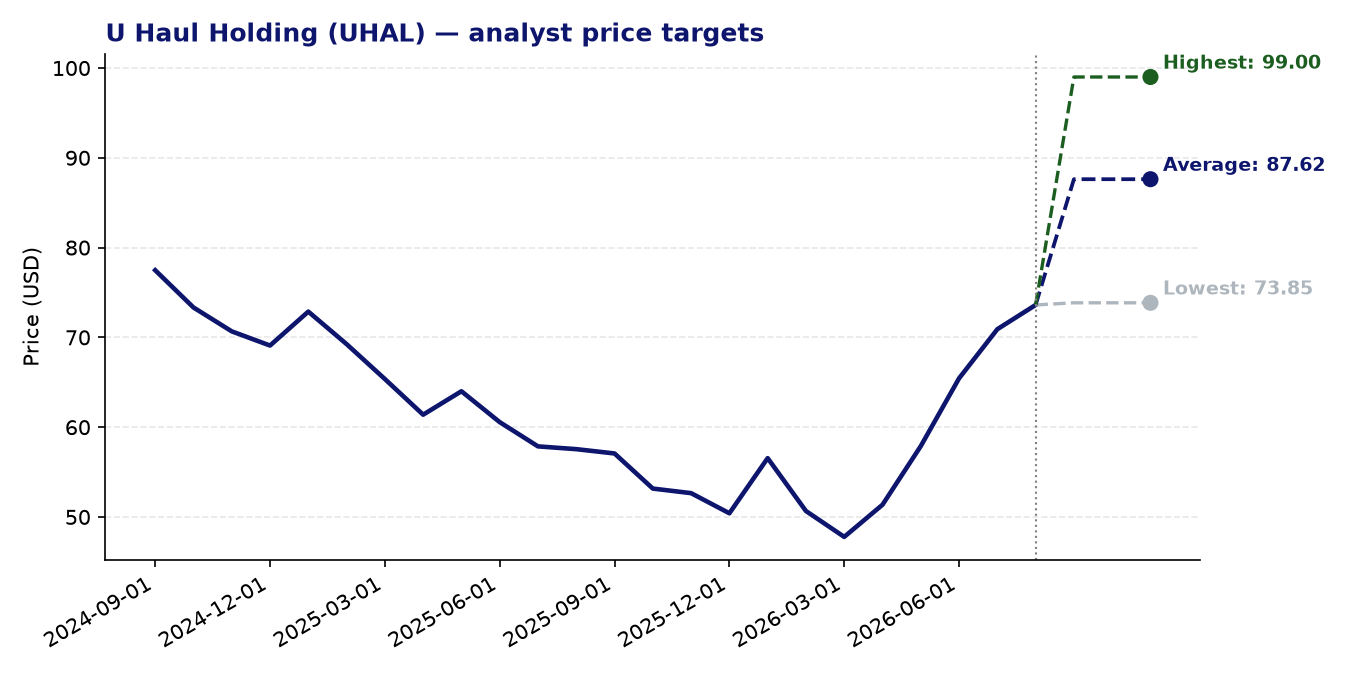
U Haul Holding (UHAL) — current price: 73.61 USD | average price target: 87.62 USD | potential: +19.0%
About U Haul Holding
- U-Haul Holding Company is a leading do-it-yourself moving and storage operator serving household and commercial customers across the United States and Canada, founded in 1945 and headquartered in Reno, Nevada.
- Its core Moving and Storage segment offers truck and trailer rentals, self-storage spaces, portable U-Box units, and a broad range of moving supplies and accessories through company-managed stores and a large independent dealer network.
- The company runs an online marketplace at uhaul.com connecting customers with independent moving-help providers and self-storage affiliates, as well as offering vehicle transport solutions such as auto transport and tow dollies.
- Two insurance segments — Property and Casualty, and Life Insurance — round out the business, providing protection packages for movers and storage customers, as well as life, health, and Medicare supplement products aimed at the senior market.
Recent news
- U-Haul’s Q4 fiscal 2026 earnings call highlighted a combination of top-line growth and pressure on profit margins, suggesting the company is navigating a more challenging cost environment even as revenues expand.
- The board approved a $350 million share repurchase programme in July 2026, citing solid cash reserves and a natural reduction in capital expenditure following a period of heavy investment in fleet renewal and storage capacity.
- Fiscal Q1 2027 results (reported August 2026) showed net profit of approximately $122.9 million, or around $0.58 per share, offering investors an early read on how the new fiscal year is developing.
- The stock has gained roughly 33% year-to-date through mid-July 2026, prompting some valuation scrutiny as analysts assess whether the recent re-rating leaves adequate margin of safety.
Strengths
- The average analyst price target of $87.62 implies roughly 19% upside from the current price of $73.61, and the lowest target of $73.85 sits only marginally above the current level, suggesting limited consensus-driven downside risk.
- A 24-month Z-score momentum reading of 2.65 is a notably strong signal, indicating that the share price has been trending well above its historical average on a risk-adjusted basis.
- The $350 million buyback programme is a tangible use of capital that could support earnings per share over time, particularly after the heavy investment cycle in fleet and storage infrastructure appears to be winding down.
- U-Haul’s diversified model — spanning truck rental, portable storage, self-storage real estate, and two insurance businesses — provides multiple revenue streams and some resilience against weakness in any single segment.
- The forward P/E of 35.4x is substantially lower than the trailing figure, pointing to meaningful anticipated earnings recovery and suggesting that current depressed earnings may not be representative of the company’s normalised earning power.
Points of attention and risks
- The trailing P/E of 525.8x reflects very thin current earnings and makes traditional valuation comparisons difficult; investors are essentially paying a significant premium based on future recovery rather than present profitability.
- EPS growth is currently slightly negative (-0.14), and the Q4 earnings call flagged margin strain, raising questions about the near-term pace of profit recovery that the elevated valuation implicitly assumes.
- The PEG ratio of 2.35 is above the threshold many value-oriented investors consider attractive, suggesting the stock is not cheap relative to its growth rate even after accounting for forward earnings estimates.
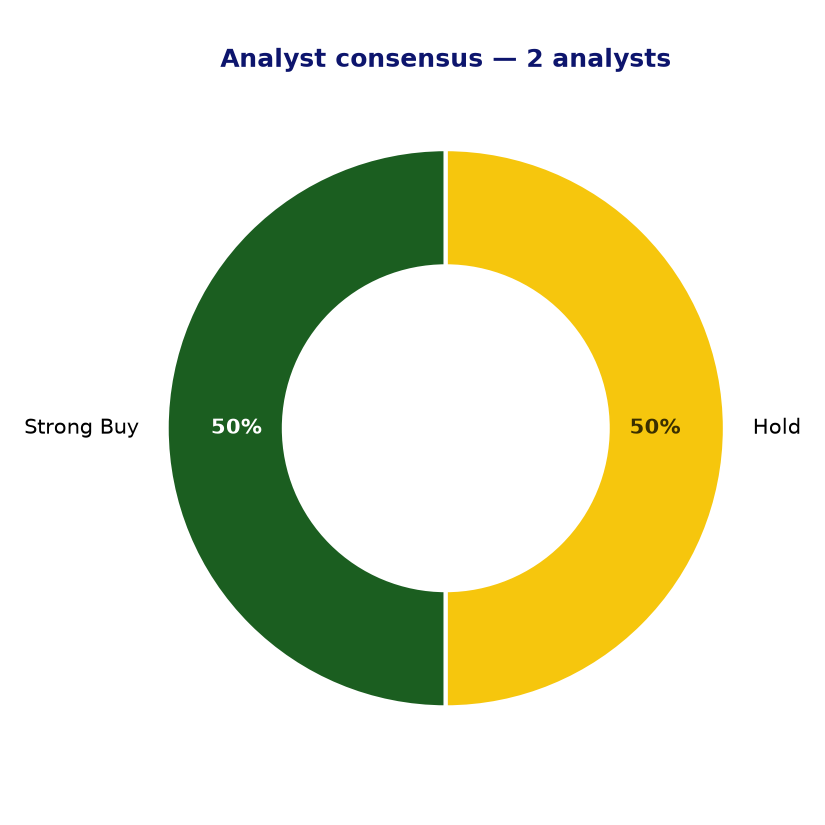
- Analyst coverage is thin — just two analysts — which limits the reliability of the consensus price target and means the stock may receive less scrutiny or liquidity support than larger-cap peers.
- The moving and storage industry is sensitive to housing market activity and broader economic confidence; a prolonged slowdown in residential mobility or consumer spending could weigh on rental volumes and pricing power.
Analyst consensus and price targets
Conclusion
U-Haul Holding presents an interesting profile for patient investors: strong price momentum, a meaningful buyback announcement, and a forward earnings picture that looks considerably more attractive than the trailing figures suggest. However, the stock has already re-rated sharply year-to-date, the thin analyst coverage limits conviction in the consensus target, and near-term margin pressures serve as a reminder that the earnings recovery is not yet fully delivered. Investors may want to weigh the quality and longevity of the business model against the execution risk still embedded in the valuation before drawing conclusions.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 19-08-2026. Not investment advice.