
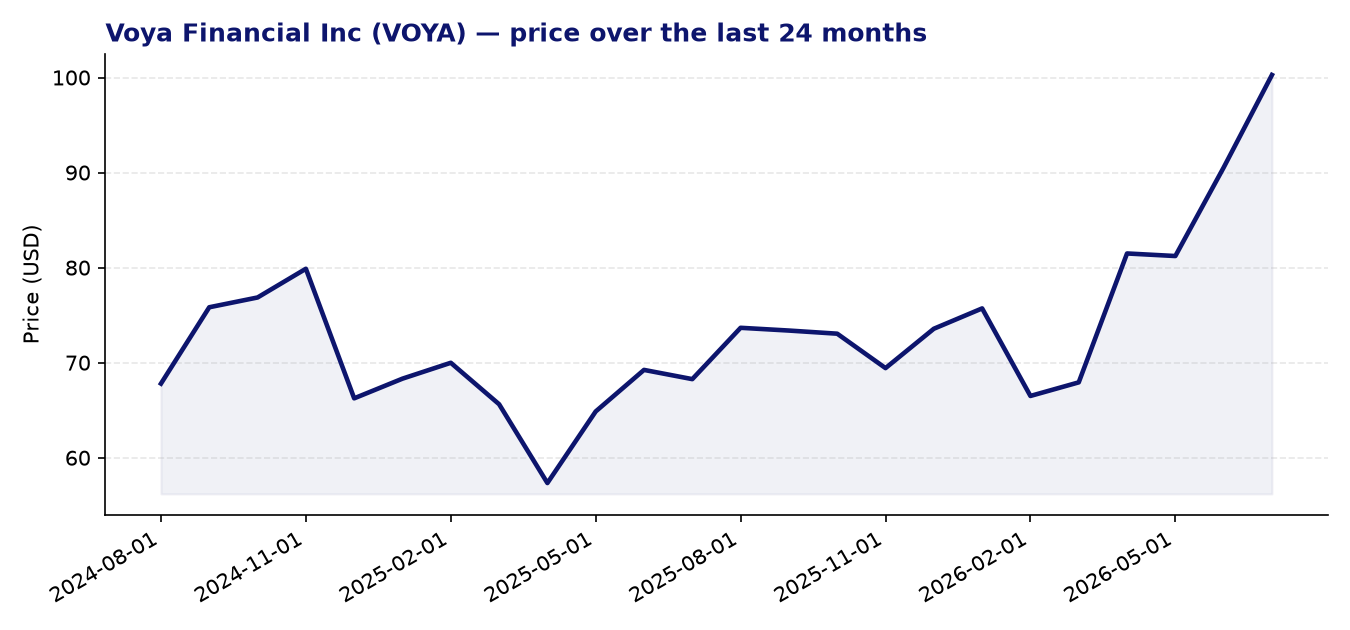
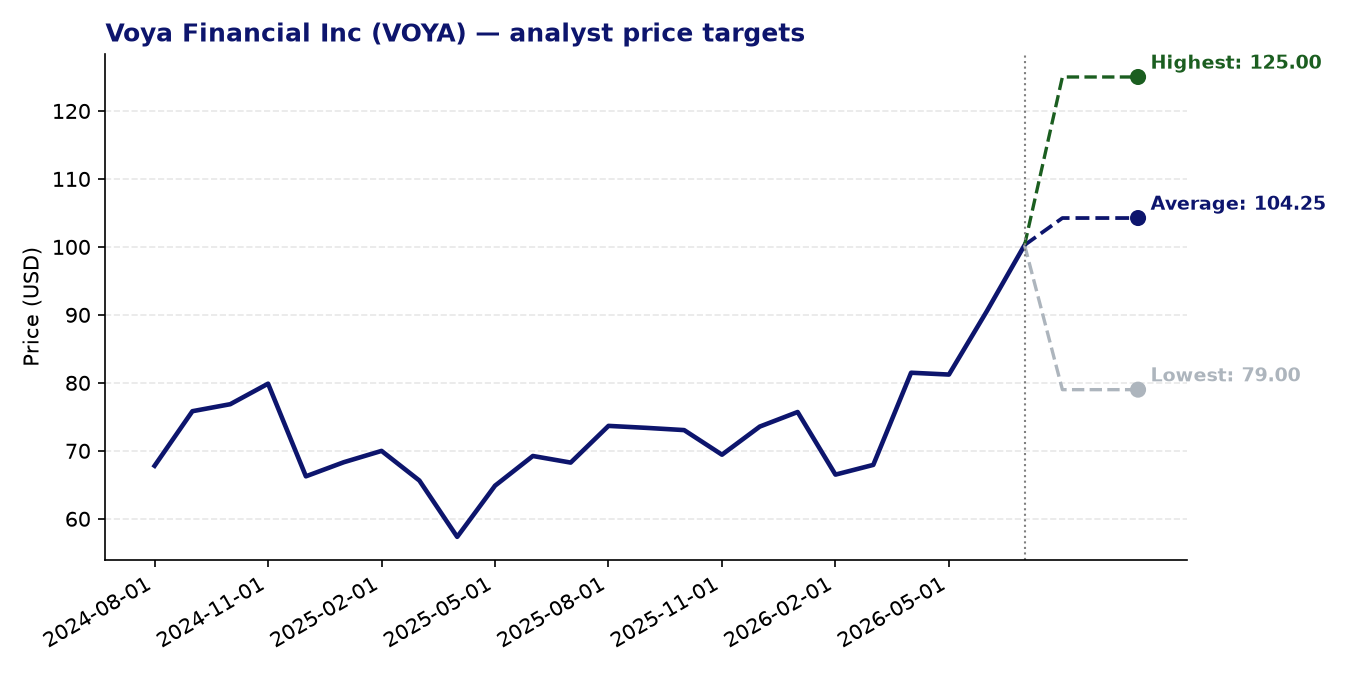
Voya Financial Inc (VOYA) — current price: 100.27 USD | average price target: 104.25 USD | potential: +4.0%
About Voya Financial Inc
- Voya Financial is a New York-based financial services company founded in 1975 (formerly ING U.S., Inc.), focused on workplace benefits, savings solutions, and investment management in the US and internationally.
- Its Retirement segment delivers full-service retirement products, recordkeeping, stable value solutions, and wealth management services to a broad range of employers, institutions, and individual customers.
- The Employee Benefits segment offers group and individual insurance products alongside health account solutions, benefits administration, and financial wellness tools, primarily targeting mid-size and large corporate employers.
- The Investment Management segment provides fixed income, equity, multi-asset, and alternative strategies to retail investors, intermediaries, and institutional clients through multiple distribution channels.
Recent news
- Voya reported adjusted operating EPS of $2.26 for Q1 2026, a 13% year-on-year increase, with trailing 12-month EPS exceeding $9.11 (up more than 20%) and return on equity holding above 18%.
- The company’s share price gained approximately 36% over the past year, meaningfully outpacing the broader industry’s roughly 19% advance, driven by strength in the Retirement and Investment Management segments.
- Barclays analyst Alex Scott reiterated a Buy rating on the stock in June 2026, maintaining a price target of $89.00, reflecting continued institutional confidence in Voya’s business trajectory.
- Following the Q1 earnings release, shares added around 2% over the subsequent month, a modest move that nonetheless lagged the broader S&P 500 during the same period.
Strengths
- Earnings momentum is solid: trailing 12-month EPS growth of over 20% and a return on equity above 18% indicate that the business is compounding capital efficiently.
- The 24-month Z-score momentum reading of 2.27 suggests the stock has exhibited meaningful positive price momentum relative to its own history, which can indicate sustained investor interest.
- The forward P/E of 8.86 looks undemanding relative to the trailing P/E of 15.15, implying the market is pricing in continued earnings expansion and leaving room for valuation re-rating.
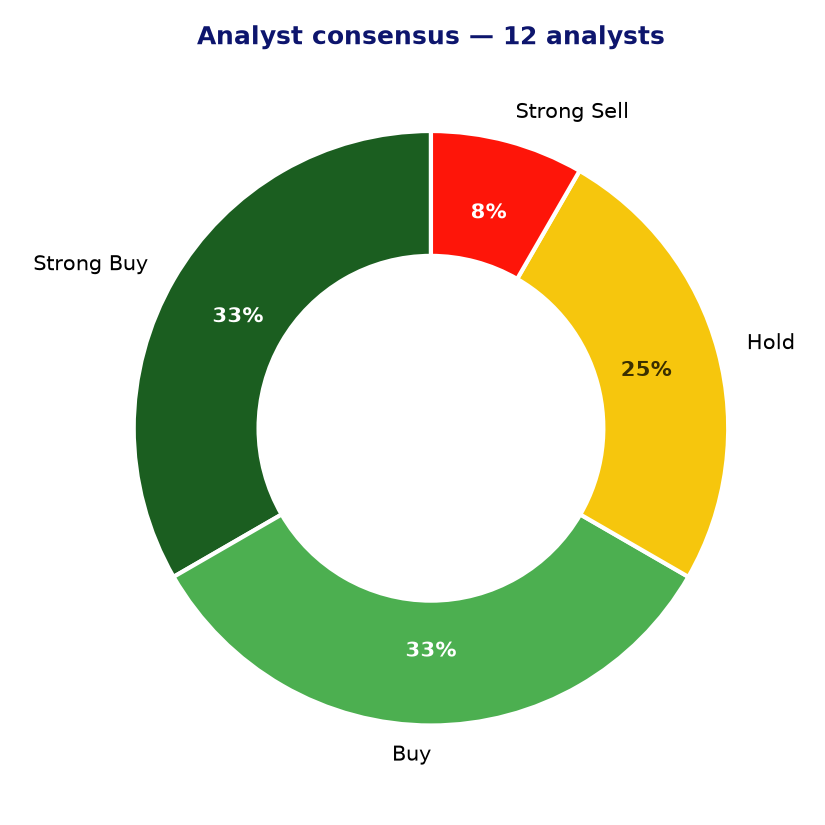
- Analyst sentiment is broadly constructive: 8 of 12 covering analysts hold a Buy or Strong Buy rating, and the consensus price target of $104.25 sits modestly above the current price of $100.27.
- Voya’s diversified three-segment model—spanning retirement, employee benefits, and investment management—provides multiple levers for revenue growth and reduces dependence on any single business line.
Points of attention and risks
- The average analyst price target of $104.25 implies only about 4% upside from current levels, suggesting much of the near-term positive news may already be reflected in the share price after the 36% run over the past year.
- The wide range of price targets ($79 to $125) points to meaningful disagreement among analysts about the company’s fair value, and one analyst carries a Strong Sell rating, indicating not all observers share the bullish view.
- The absence of a PEG ratio (due to the data being unavailable) makes it harder to assess whether the current valuation fully accounts for the pace of earnings growth, adding a degree of uncertainty to valuation analysis.
- As a financial conglomerate with insurance and investment management exposure, Voya is sensitive to interest rate movements, equity market volatility, and credit conditions—all of which can affect both asset values and underwriting profitability.
- The modest 2% share price gain in the month following the most recent earnings report, which lagged the S&P 500, may indicate that the market’s near-term expectations are already high and incremental upside catalysts are less obvious.
Analyst consensus and price targets
Conclusion
Voya Financial presents a picture of a business delivering consistent earnings growth, supported by a diversified model across retirement services, employee benefits, and investment management. The forward valuation remains relatively modest, and analyst sentiment is largely positive, though the limited consensus price target upside and the stock’s strong prior-year run suggest that patience may be required for the next leg of appreciation. Investors considering a position would need to weigh the quality of the underlying earnings momentum against the possibility that current pricing already captures much of the near-term opportunity.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 30-07-2026. Not investment advice.