
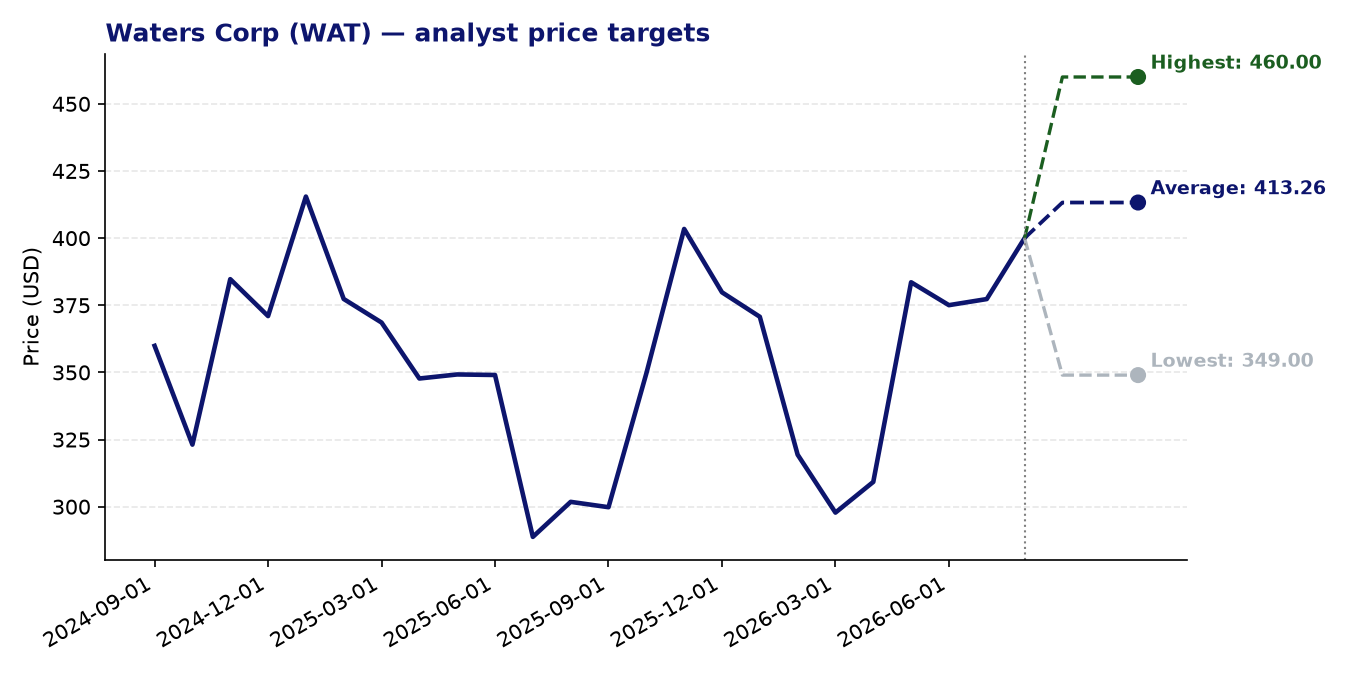
Waters Corp (WAT) — current price: 400.00 USD | average price target: 413.26 USD | potential: +3.3%
About Waters Corp
- Waters Corporation, founded in 1958 and headquartered in Milford, Massachusetts, develops and sells analytical instruments and workflow solutions across Asia, the Americas, and Europe.
- Its core Waters segment produces liquid chromatography and mass spectrometry systems, along with consumables such as chromatography columns, widely used in pharmaceutical, biochemical, and environmental research.
- The TA segment manufactures thermal analysis, rheometry, and calorimetry instruments used to assess the properties of materials ranging from pharmaceuticals to polymers and metals.
- The company also develops software that integrates with its own instruments as well as those of third-party manufacturers, supporting laboratory data management and analysis.
- Customers span pharmaceutical and biotech companies, government agencies, academic institutions, and industrial laboratories, with applications in drug discovery, quality assurance, and nutritional safety testing.
Recent news
- Waters is scheduled to report its Q2 2026 financial results on 4 August 2026, with a live webcast available to investors — the announcement signals continued routine transparency with the market.
- A review of Q1 2026 earnings across the research tools and consumables sector ranked Waters among the standout performers, suggesting solid relative execution compared with sector peers.
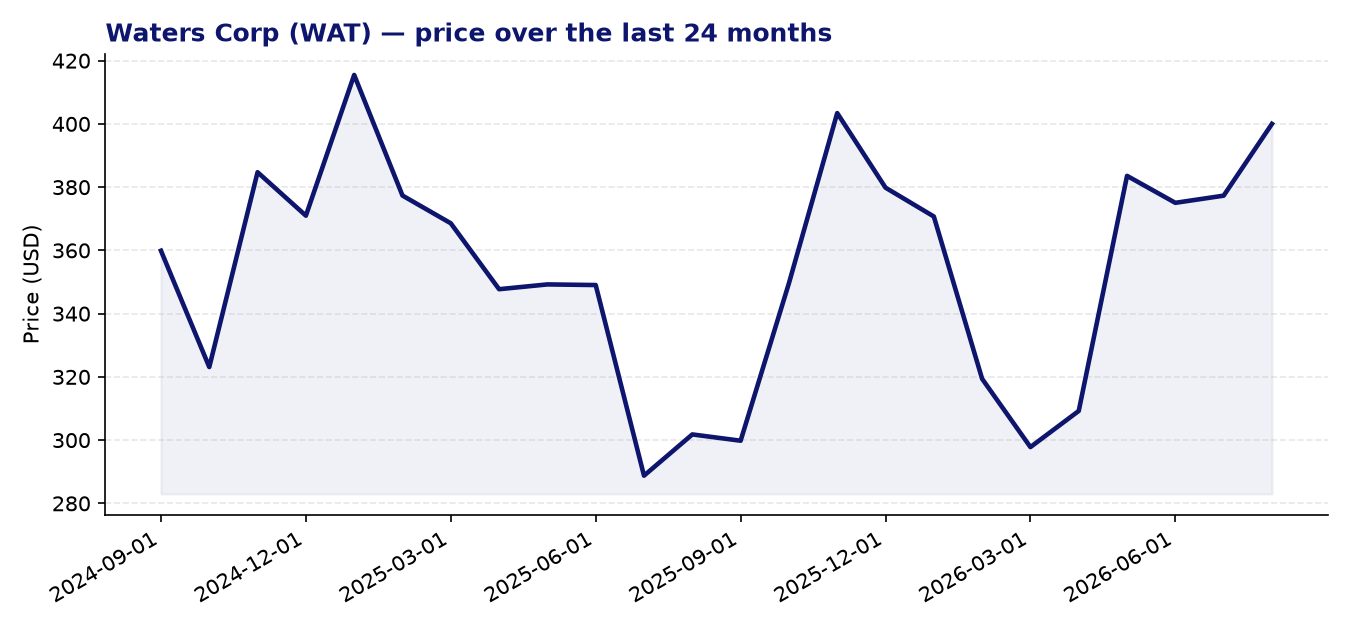
- A bullish investment thesis circulating in mid-May highlighted Waters as a potentially attractive holding, with shares trading around $302 at that time — notably below the current price level.
- Ahead of the upcoming Q2 report, analyst previews note the company’s $37 billion market capitalisation and its continued focus on high-performance liquid chromatography and mass spectrometry as key revenue drivers.
Strengths
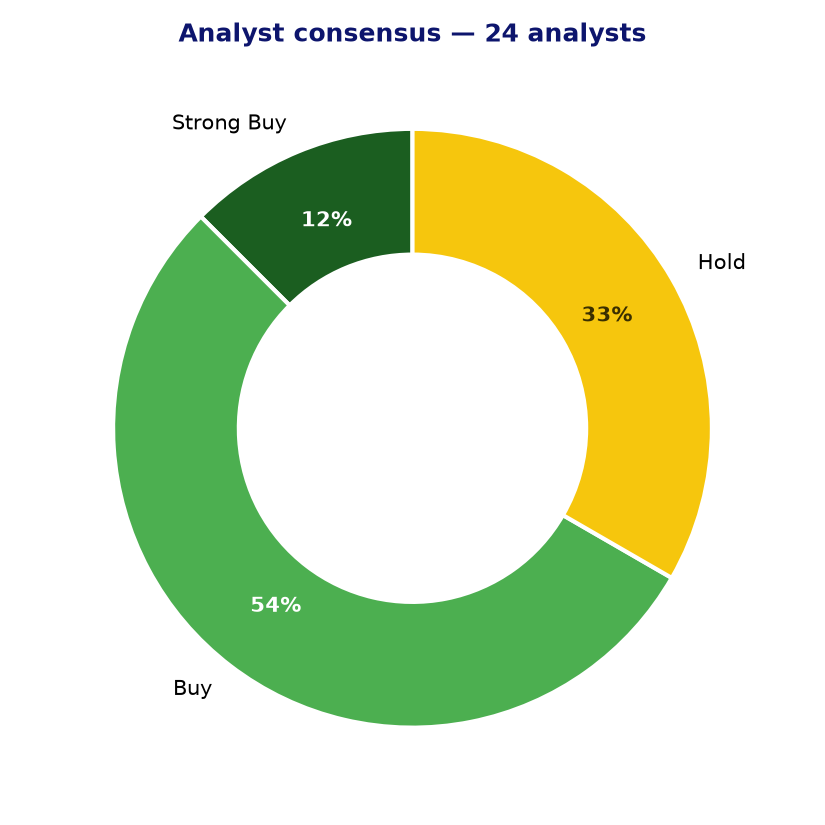
- Analyst sentiment is broadly constructive: of 24 analysts covering the stock, 16 rate it buy or strong buy, with no sell ratings recorded at this time.
- The 24-month Z-score momentum reading of 2.20 indicates that the stock has demonstrated meaningful positive price momentum relative to its own history, suggesting sustained market interest.
- The forward P/E of 24.26 is considerably more moderate than the trailing P/E of 50.83, implying that earnings growth is expected to accelerate and that the valuation becomes more reasonable on a forward-looking basis.
- Waters operates in a structurally resilient end market: demand for analytical instruments in pharmaceutical development, regulatory testing, and life science research tends to hold up well across economic cycles.
- The consumables and software components of the business — chromatography columns and data software — provide a recurring revenue stream that complements the more lumpy instrument sales cycle.
Points of attention and risks
- The average analyst price target of $413.26 implies only modest upside of around 3.3% from the current price of $400, which may limit near-term appeal for investors seeking a wider margin of safety.
- The trailing P/E of 50.83 is elevated, and with no current EPS growth figure available, it is difficult to assess with confidence whether near-term earnings momentum justifies that multiple.
- The PEG ratio of 1.69 suggests the stock is not inexpensive relative to its growth prospects, which could make it vulnerable to de-rating if earnings disappoint or guidance is cut.
- The wide spread between the lowest and highest analyst price targets ($349 to $460) reflects meaningful uncertainty about the company’s near-term earnings trajectory.
- As a supplier heavily exposed to pharmaceutical and biotech R&D budgets, Waters is sensitive to capital expenditure cycles in those industries; any prolonged tightening of biopharma spending could weigh on instrument demand.
Analyst consensus and price targets
Conclusion
Waters Corporation occupies a well-established position in the analytical instruments market, with a diversified product range, a sticky consumables revenue base, and broadly positive analyst sentiment. However, the current share price already reflects much of that quality, with limited consensus upside to the average price target and a trailing valuation that demands continued earnings delivery. Investors may find the story more compelling after the Q2 2026 results on 4 August provide clearer visibility on whether growth is accelerating in line with the more reasonable forward multiple.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 05-08-2026. Not investment advice.