
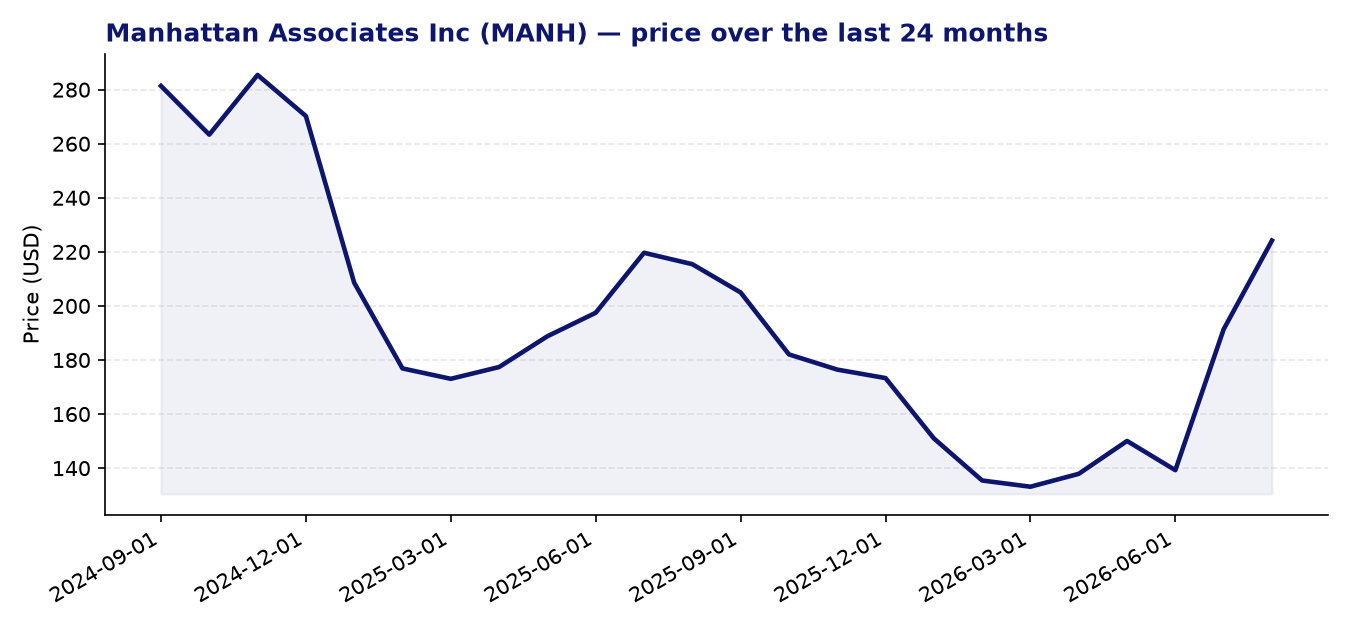
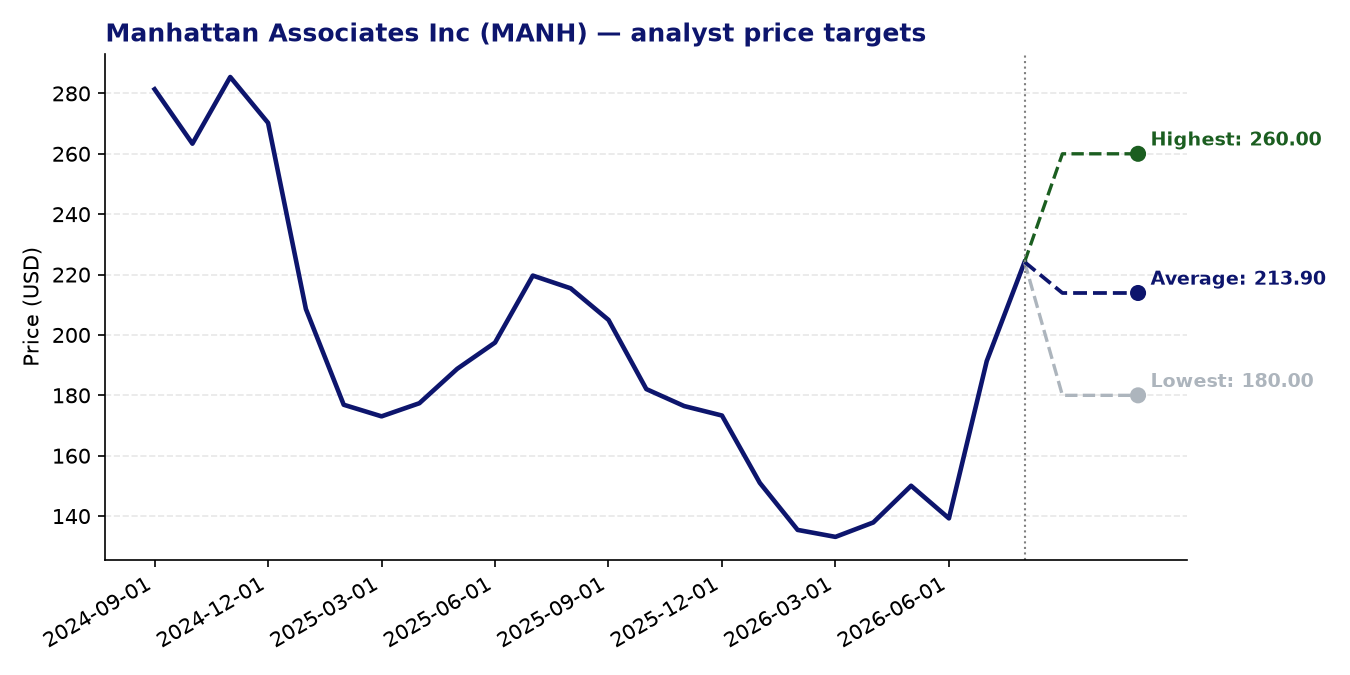
Manhattan Associates Inc (MANH) — current price: 224.17 USD | average price target: 213.90 USD | potential: -4.6%
About Manhattan Associates Inc
- Manhattan Associates develops and maintains enterprise software solutions for supply chain management, warehouse operations, and omni-channel retail, serving clients across retail, logistics, food and grocery, life sciences, and government sectors.
- Its flagship cloud-native platform, Manhattan Active, covers warehouse management, transportation management, order management, and store fulfilment, and is designed to be continuously updated without version upgrades.
- The company supplements its software business with professional services including implementation consulting, training, and change management, as well as the resale of related hardware peripherals.
- Founded in 1990 and headquartered in Atlanta, Georgia, Manhattan Associates operates across the Americas, EMEA, and Asia-Pacific through direct sales teams and partnership agreements.
Recent news
- In its second-quarter 2026 earnings report, Manhattan Associates delivered adjusted earnings per share of $1.39, ahead of the consensus estimate of $1.31 and above the prior-year figure of $1.31.
- Cloud subscription revenue surged 26% year-on-year to become the company’s largest individual revenue line, reflecting continued customer migration to the Manhattan Active platform.
- The quarter marked the company’s third consecutive record bookings period, with remaining performance obligations climbing 23% to approximately $2.47 billion, signalling a solid near-term revenue pipeline.
- Separately, Zacks Investment Research highlighted Manhattan Associates as a top-ranked momentum stock, consistent with its elevated 24-month Z-score momentum reading.
Strengths
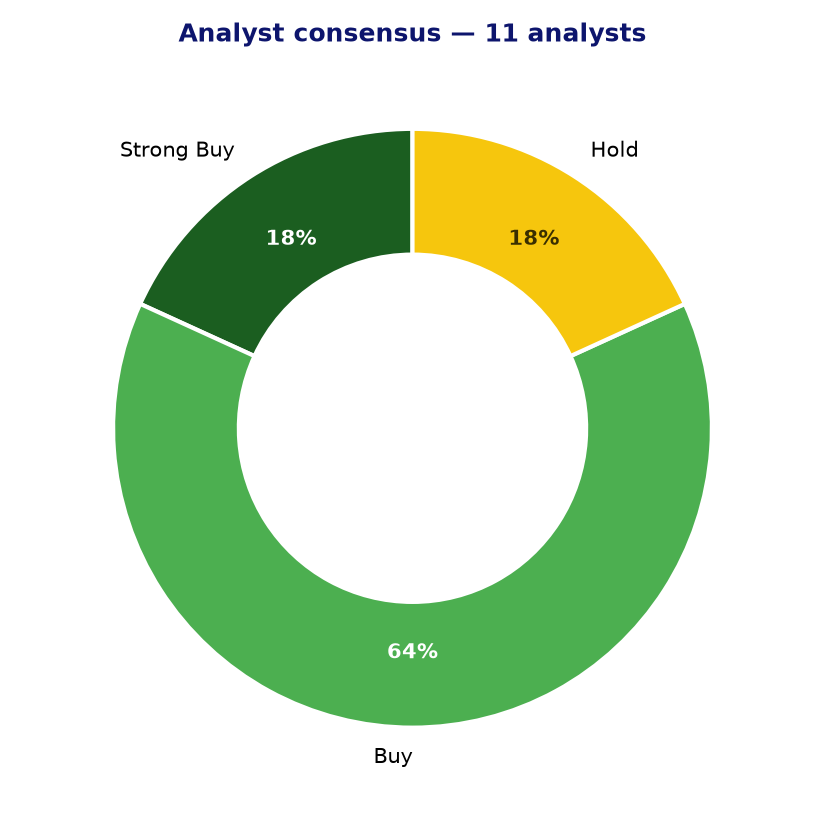
- Nine of eleven covering analysts rate the stock a buy or strong buy, reflecting broad confidence in the company’s competitive positioning within supply chain software.
- The 24-month Z-score momentum reading of 3.04 is notably high, indicating sustained relative price strength compared to the broader market.
- Three consecutive record bookings quarters and a $2.47 billion remaining performance obligations balance provide meaningful near-term revenue visibility.
- The accelerating shift to cloud subscriptions supports a more predictable, recurring revenue model, which typically commands valuation resilience through economic cycles.
- The forward P/E of 36.53 represents a material discount to the trailing P/E of 64.23, implying that earnings growth is expected to compress the multiple meaningfully over the next twelve months.
Points of attention and risks
- At the current price of $224.17, the stock trades approximately 4.6% above the average analyst price target of $213.90, suggesting limited near-term upside is already priced in on a consensus basis.
- The trailing P/E of 64.23 and a PEG ratio of 2.57 indicate a demanding valuation that leaves little margin for error should growth disappoint or macro conditions deteriorate.
- Reported EPS growth is currently marginally negative (-0.11), and while adjusted figures tell a more positive story, the gap between GAAP and adjusted earnings warrants monitoring.
- Manhattan Associates operates in a competitive enterprise software market, facing pressure from large diversified vendors such as SAP and Oracle, as well as nimble specialist competitors.
- The company’s fortunes are closely tied to capital spending cycles in retail and logistics; any prolonged softness in those end-markets could weigh on new bookings and implementation revenues.
Analyst consensus and price targets
Conclusion
Manhattan Associates presents a well-established franchise in supply chain software, underpinned by strong cloud adoption momentum, a growing backlog, and a broadly supportive analyst community. However, the stock’s current price already exceeds the average analyst price target, and the valuation multiples reflect a level of optimism that requires continued execution at or above recent rates. Investors weighing an entry at current levels should consider whether the fundamental quality of the business justifies the premium relative to both peers and the analysts’ own price objectives.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 28-08-2026. Not investment advice.