
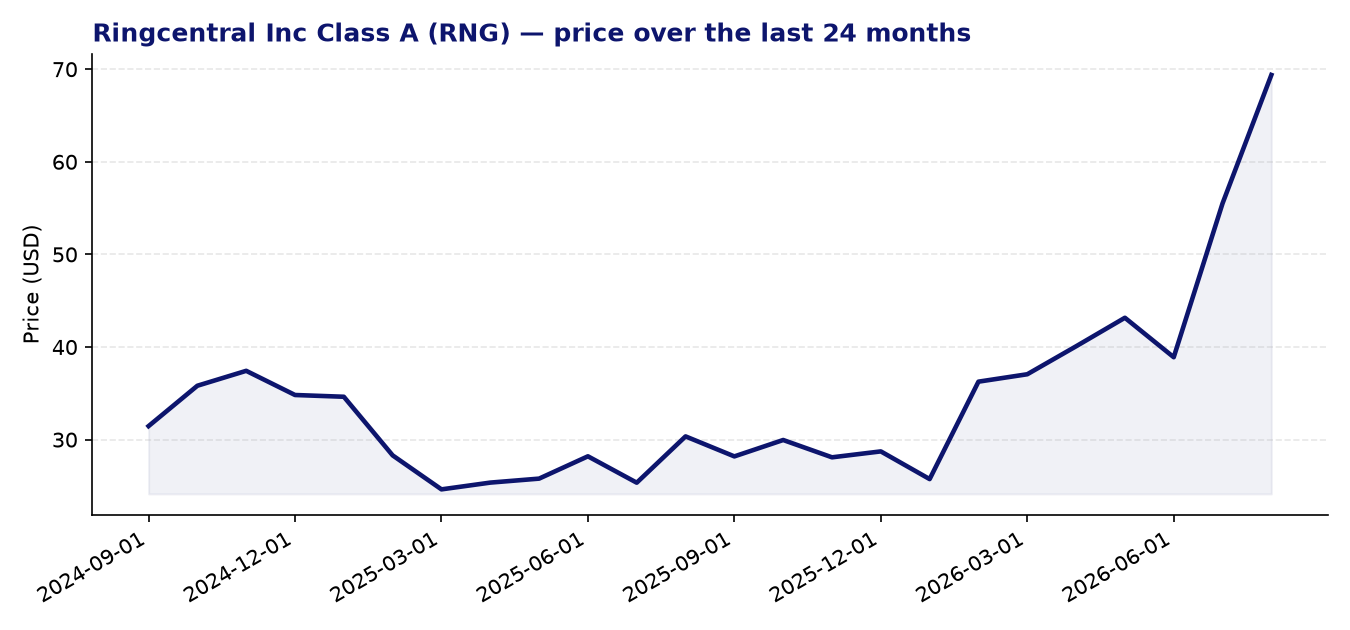
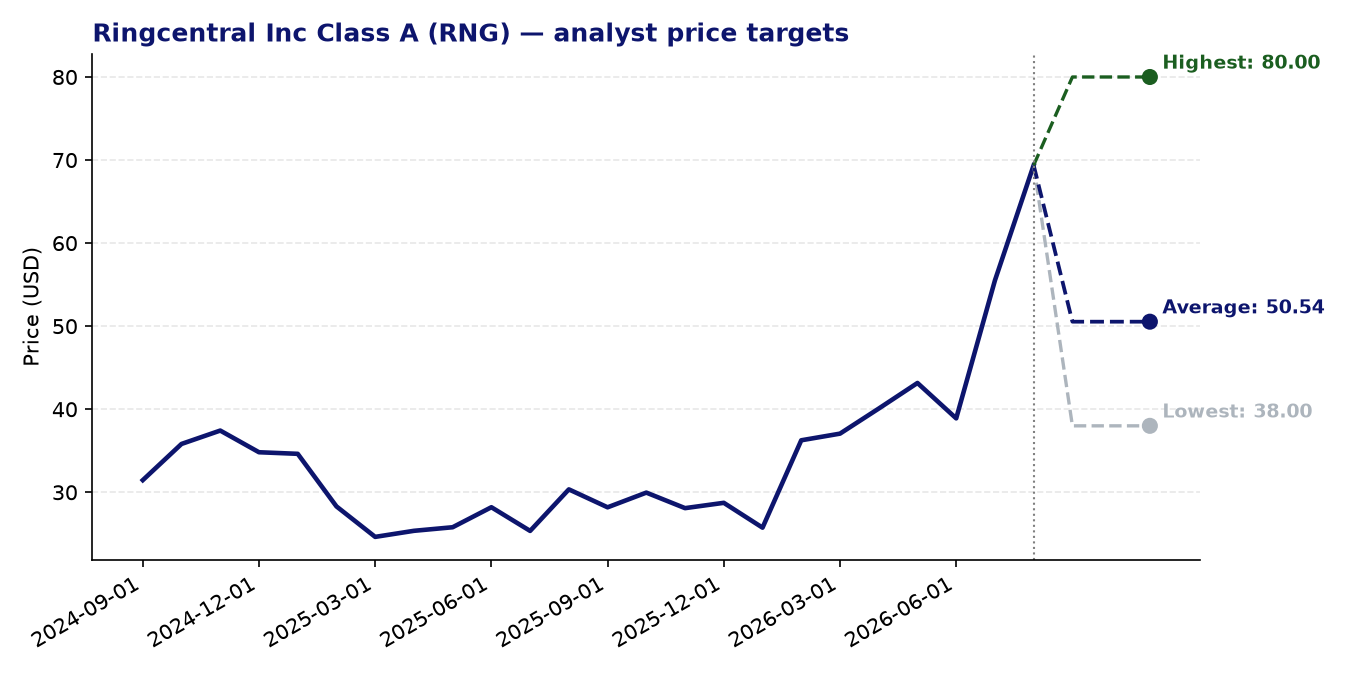
Ringcentral Inc Class A (RNG) — current price: 69.38 USD | average price target: 50.54 USD | potential: -27.2%
About Ringcentral Inc Class A
- RingCentral is a cloud-based business communications platform founded in 1999 and headquartered in Belmont, California, offering unified communications, contact centre, video collaboration, and messaging services.
- Its core products include RingEX (AI-powered unified communications), RingCentral Contact Center, and RingCX (contact centre-as-a-service with CRM integrations), all increasingly built around artificial intelligence capabilities.
- The company offers a growing suite of AI tools including an AI Receptionist, AI Agent Assist, AI Supervisor Assist, and automated quality management, targeting both operational efficiency and customer engagement.
- RingCentral serves a broad range of industries — from healthcare and financial services to government and retail — selling to enterprises and SMBs via direct channels, resellers, global service providers, and distribution partners.
Recent news
- RingCentral’s second-quarter 2026 results came in ahead of Wall Street expectations, with the company also raising its forward guidance, triggering a sharp single-day share price move of approximately 27%.
- Revenue grew around 5.9% year-over-year in Q2, while operating margins reached approximately 23%, suggesting the business is achieving greater operational discipline alongside its AI-led product transition.
- The company’s AI-focused contact centre products are reported to be generating net revenue retention rates above 100%, indicating that existing customers are expanding their spending on these newer solutions.
- With shares up roughly 40% year-to-date heading into late July 2026, at least one analyst has assigned a Neutral rating with a price target of $55, noting limited near-term upside following the post-earnings surge.
Strengths
- The PEG ratio of 0.36 is notably low relative to the sector, suggesting the market may not yet be fully pricing in the company’s earnings growth trajectory despite the recent share price appreciation.
- The forward P/E of 12.4x stands in sharp contrast to the trailing P/E of 55.5x, implying that analyst consensus anticipates a significant step-up in earnings power over the next twelve months.
- A 24-month Z-score momentum reading of 2.17 places RingCentral in clearly positive momentum territory, consistent with the stock’s strong year-to-date performance.
- AI-driven products with net retention rates above 100% indicate that upsell and cross-sell dynamics within the existing customer base are strengthening, which supports revenue visibility.
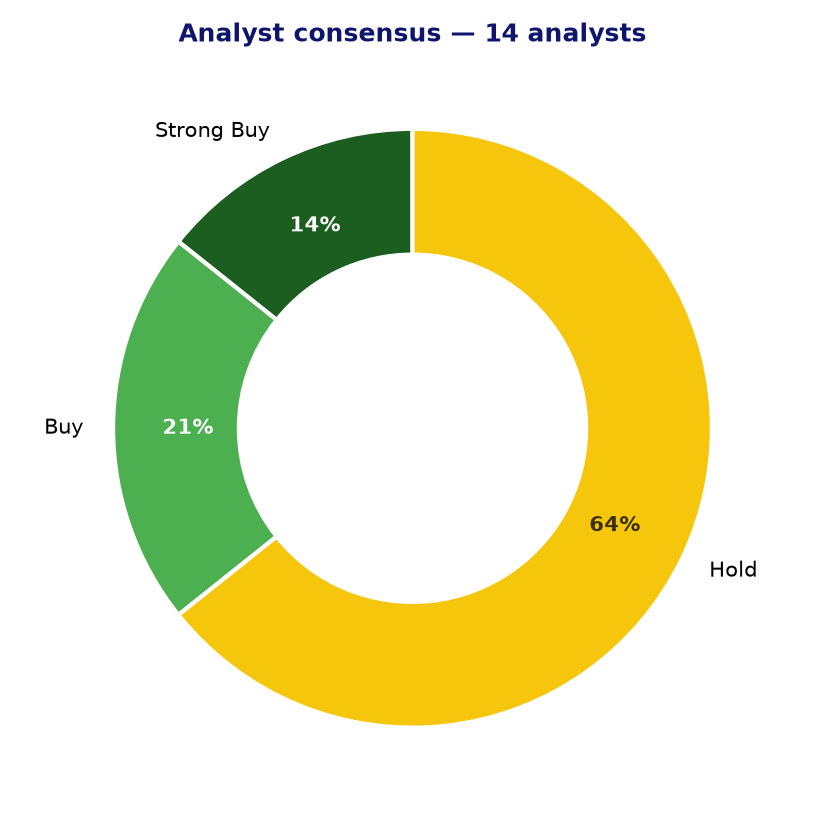
- Two of 14 covering analysts rate the stock a strong buy and three rate it a buy, reflecting a cautiously constructive overall analyst stance even after a substantial price re-rating.
Points of attention and risks
- The average analyst price target of $50.54 sits approximately 27% below the current share price of $69.38, meaning the consensus view implies the stock has moved ahead of fair value following its post-earnings surge.
- The trailing P/E of 55.5x remains elevated in absolute terms, and the forward valuation thesis relies heavily on a substantial earnings improvement that has yet to be fully delivered.
- Nine of 14 analysts hold a neutral stance, suggesting that the broader analyst community believes much of the near-term upside has already been reflected in the price.
- Revenue growth of around 6% year-over-year, while improving, remains modest for a software company trading at current multiples, and any deceleration could pressure the valuation.
- The competitive landscape for cloud communications and AI-powered contact centre solutions is intense, with larger, better-capitalised rivals such as Microsoft, Cisco, and Salesforce investing heavily in adjacent capabilities.
Analyst consensus and price targets
Conclusion
RingCentral’s Q2 results demonstrate meaningful operational progress — improving margins, AI product traction, and a raised outlook — and the low PEG ratio alongside strong momentum metrics make the fundamental picture more interesting than a simple glance at the trailing P/E might suggest. However, with the consensus analyst price target pointing to material downside from current levels and the majority of covering analysts sitting on the sidelines, the market appears to have priced in a good deal of the near-term optimism in a very short period. Investors may find the long-term AI-driven narrative compelling, but the current entry point warrants careful consideration of the gap between price and consensus value.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 28-08-2026. Not investment advice.