
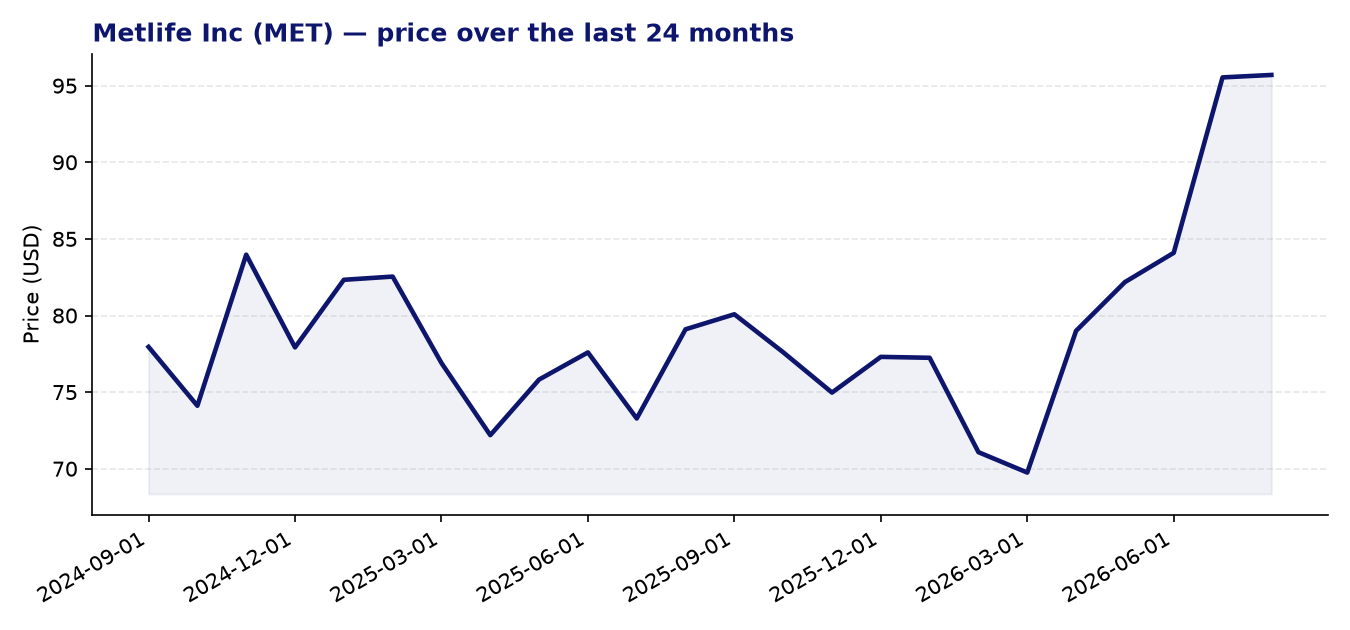
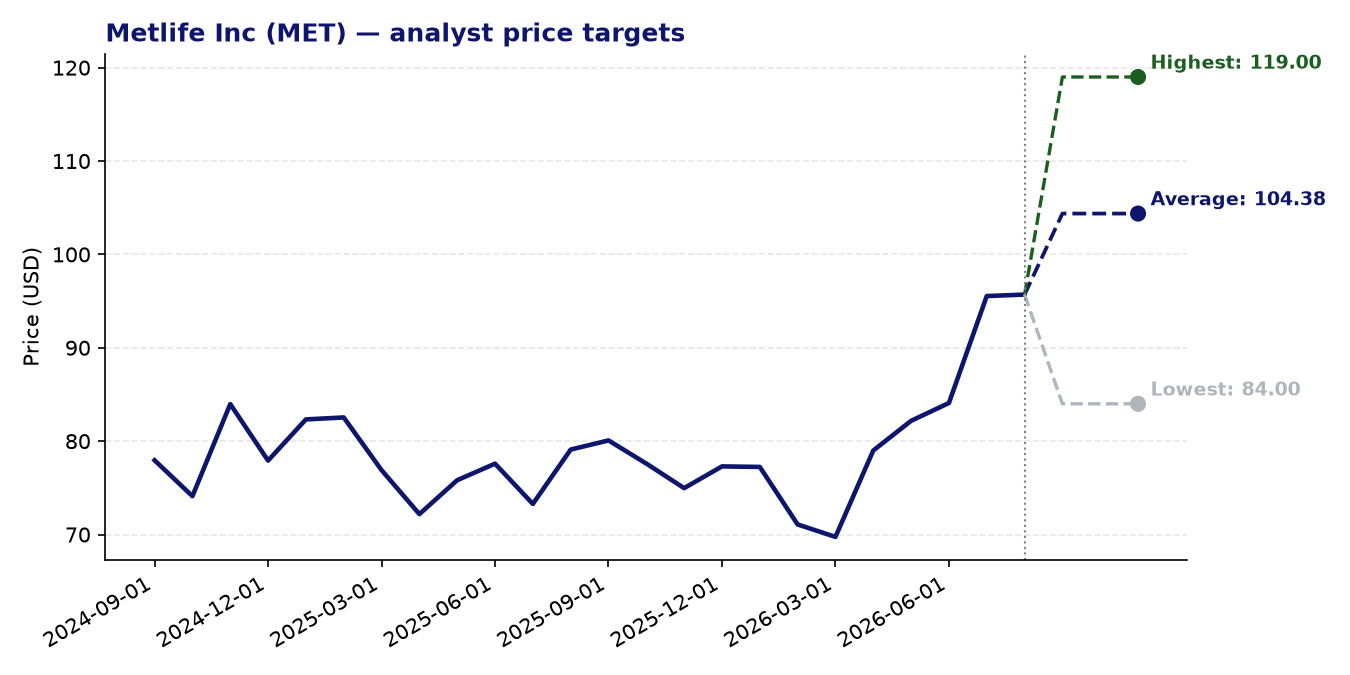
Metlife Inc (MET) — current price: 95.70 USD | average price target: 104.38 USD | potential: +9.1%
About Metlife Inc
- MetLife is one of the world’s largest financial services groups, offering life insurance, annuities, employee benefits, and asset management across six operating segments.
- Its domestic operations centre on Group Benefits — covering life, dental, disability, and vision products for employers — and Retirement and Income Solutions, which includes pension risk transfers and institutional annuities.
- Internationally, MetLife operates dedicated segments in Asia, Latin America, and EMEA, providing a broad range of protection, savings, and pension products tailored to local markets.
- The company also runs a legacy segment, MetLife Holdings, which manages older in-force business including variable and universal life policies and long-term care products.
Recent news
- MetLife’s second-quarter 2026 results came in ahead of analyst expectations, with adjusted earnings per share rising 20% year-over-year to $2.43, supported by favourable underwriting experience and broad-based volume growth.
- Following the strong quarterly print, commentary around the stock has shifted to the sustainability of capital levels and the trajectory of the retirement and group benefits divisions as key signposts for the outlook.
- Analyst coverage tracked by aggregators places MetLife’s market capitalisation at approximately $61.9 billion, reflecting the stock’s recent stability while the market awaits further capital allocation signals from management.
Strengths
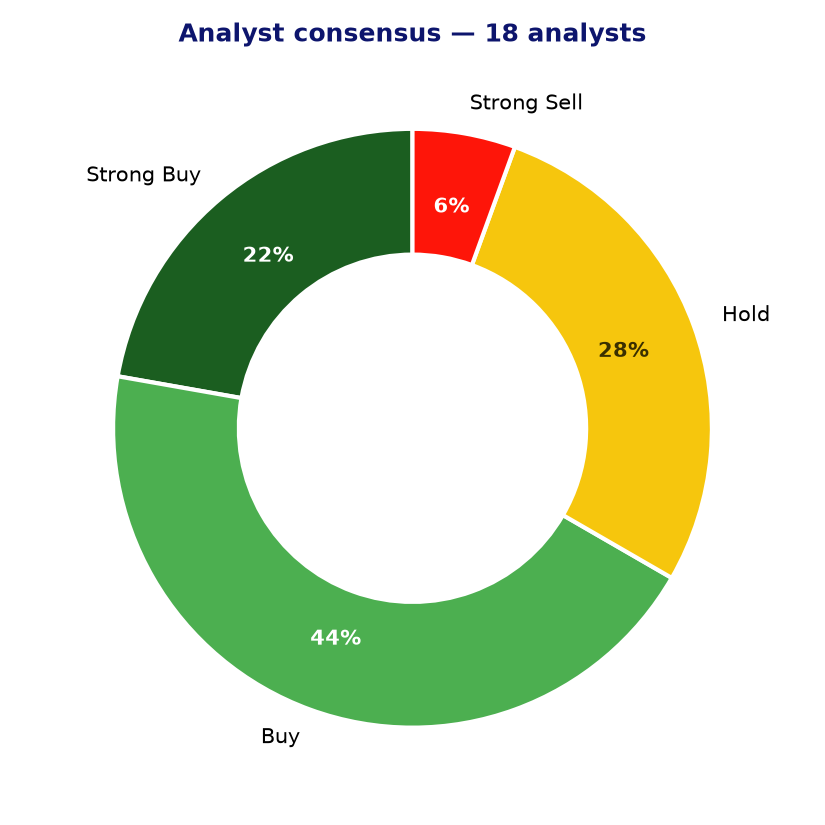
- The analyst consensus leans constructively, with 12 of 18 covering analysts rating the stock a buy or strong buy, and the average price target of $104.38 implying around 9% upside from the current price of $95.70.
- A 24-month Z-score momentum reading of 2.32 suggests the stock has shown meaningfully positive price momentum relative to its own history, which may reflect growing confidence in earnings delivery.
- Valuation appears undemanding: a forward P/E of 8.78 and a PEG ratio of 0.53 indicate the market is not pricing in aggressive growth expectations, potentially offering a margin of safety for patient investors.
- The 20% year-over-year jump in adjusted EPS in the most recent quarter points to genuine operational leverage, driven by disciplined underwriting and expanding volumes rather than financial engineering.
- MetLife’s diversified geographic footprint across Asia, Latin America, and EMEA reduces dependence on any single market and provides exposure to structurally growing insurance demand in emerging economies.
Points of attention and risks
- The trailing P/E of 18.33 sits notably above the forward P/E of 8.78, which raises questions about earnings visibility and whether the implied step-up in profitability will materialise as expected.
- EPS growth of 0.01 on a trailing basis is negligible, suggesting that the stronger recent quarter may partly reflect timing or one-off underwriting favourable developments rather than a sustained upward trend.
- The range between the lowest and highest analyst price targets — $84 to $119 — is unusually wide, reflecting genuine disagreement about the company’s earnings power and capital position going forward.
- One analyst carries a strong sell rating, a reminder that not all market participants share the broadly positive view; concerns may centre on long-tail liability risks, including legacy long-term care exposure in MetLife Holdings.
- Life insurers remain sensitive to interest rate movements, credit spread volatility, and equity market conditions, all of which can affect investment income, reserve adequacy, and the attractiveness of annuity products.
Analyst consensus and price targets
Conclusion
MetLife presents a mixed but broadly constructive picture: the recent earnings beat, reasonable valuation multiples, and positive price momentum are genuine points in its favour, while questions around legacy liabilities, the wide dispersion of analyst targets, and the gap between trailing and forward earnings multiples warrant careful attention. The company’s diversified business model — spanning group benefits, retirement solutions, and international markets — provides a degree of resilience, but investors should weigh the sector’s inherent sensitivity to macroeconomic and interest rate conditions. Those with a longer time horizon and an interest in the insurance sector may find MetLife’s current positioning worth monitoring as further capital allocation decisions come into focus.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 24-08-2026. Not investment advice.