
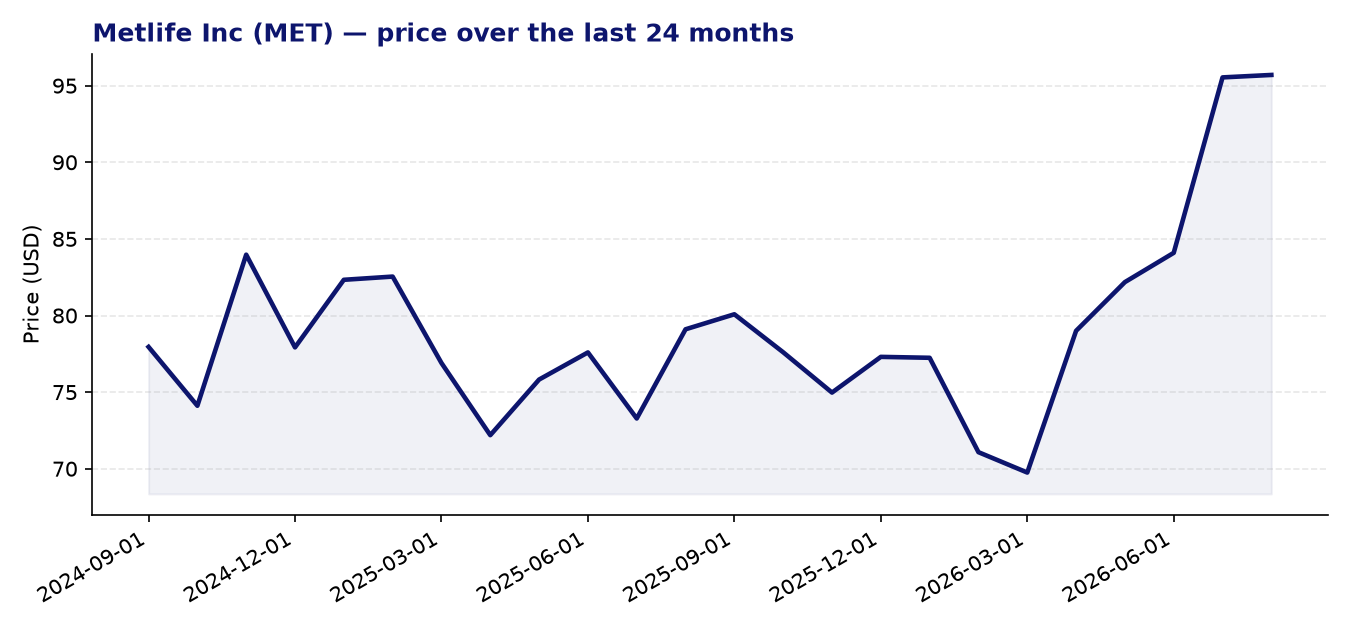
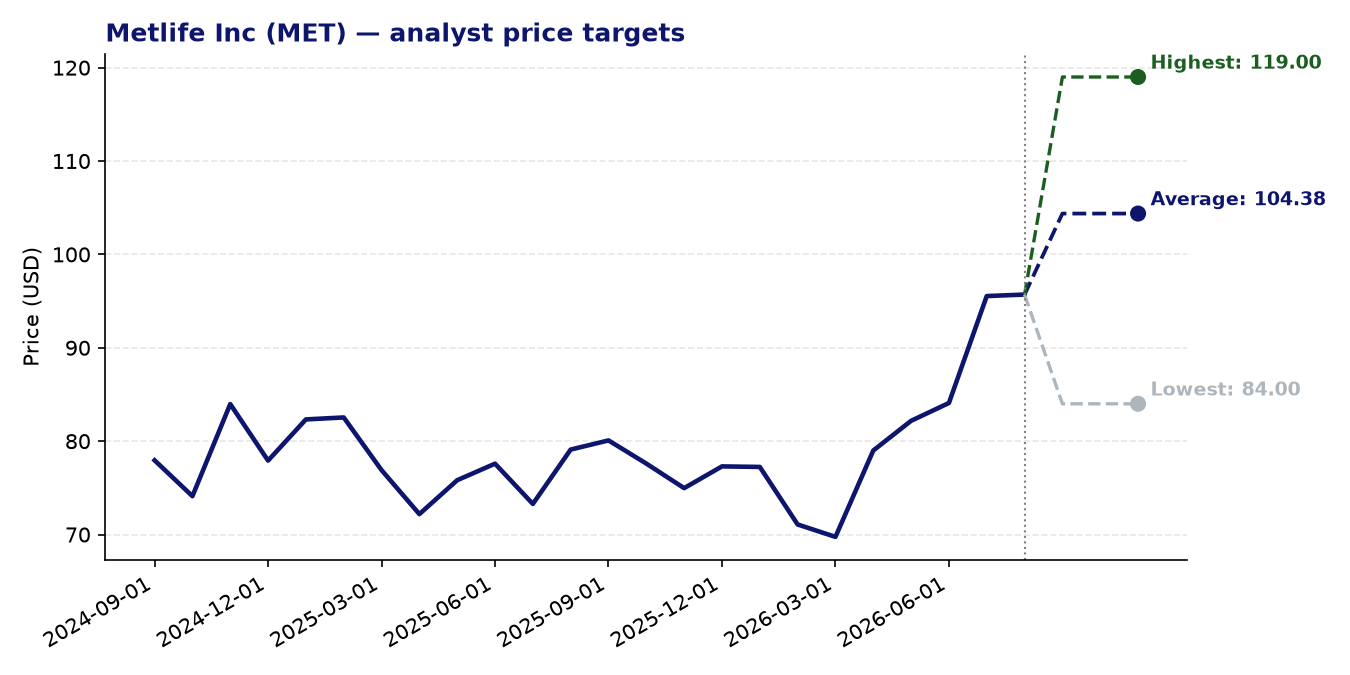
Metlife Inc (MET) — current price: 95.70 USD | average price target: 104.38 USD | potential: +9.1%
About Metlife Inc
- MetLife is a major global financial services group offering insurance, annuities, employee benefits, and asset management across six operating segments, including Group Benefits, Retirement and Income Solutions, and four international regions.
- The company serves both individual and institutional clients with products ranging from life and disability insurance to pension risk transfers, structured settlements, and capital markets investment products.
- Its international footprint spans Asia, Latin America, Europe, the Middle East, and Africa, giving it meaningful exposure to diverse economic cycles and growth markets.
- MetLife also operates MetLife Investment Management (MIM), an institutional asset management platform that adds a fee-based earnings dimension alongside its traditional insurance underwriting business.
Recent news
- MetLife reported second-quarter 2026 results that surpassed analyst expectations, with adjusted earnings per share rising approximately 20% year-over-year to $2.43, supported by favorable underwriting conditions and volume growth across key segments.
- Management announced a new $3 billion share buyback authorisation, signalling confidence in the capital position and a continued commitment to returning cash to shareholders.
- The company’s CEO highlighted what he described as a particularly strong quarter, noting that MetLife’s two complementary earnings engines — underwriting and investment management — each contributed roughly equally to results.
- Investor attention heading into the result had centred on the strength of the Group Benefits segment and the overall capital position, both of which appear to have met or exceeded expectations.
Strengths
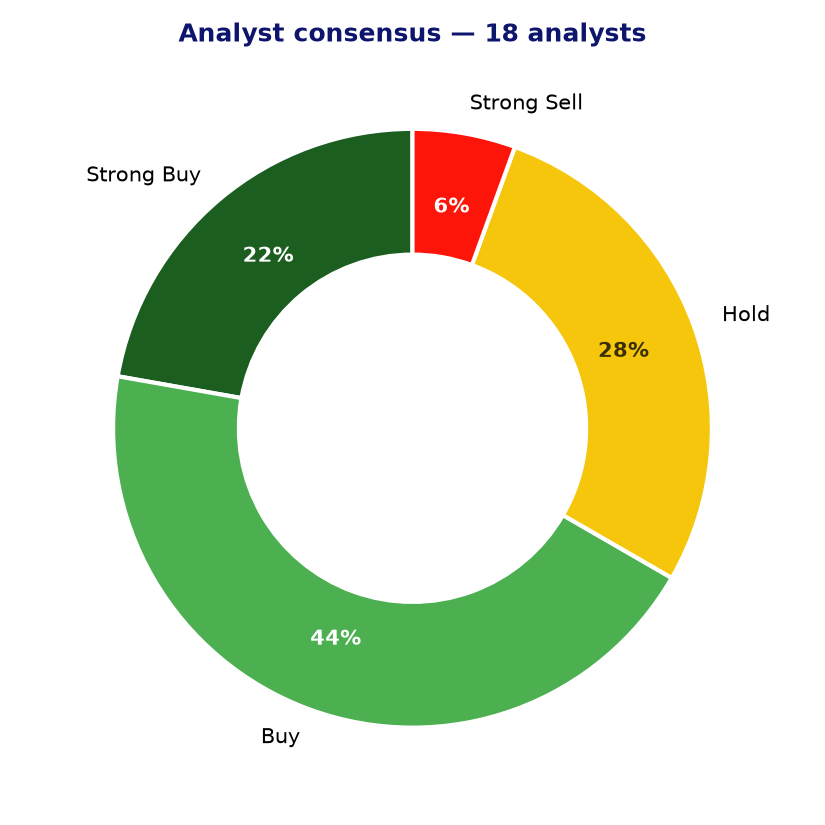
- The analyst community is broadly constructive, with 12 out of 18 analysts rating MetLife a buy or strong buy and an average price target of $104.38, implying around 9% upside from the current price of $95.70.
- The forward P/E of 8.78 and a PEG ratio of 0.53 suggest the shares are priced modestly relative to near-term earnings expectations, which may appeal to valuation-conscious investors.
- A 24-month Z-score momentum reading of 2.32 indicates the stock has shown meaningful positive price momentum relative to its own history, which can reflect improving market sentiment or fundamentals.
- The 20% year-over-year increase in adjusted EPS in the most recent quarter, together with a new $3 billion buyback, demonstrates both operational progress and management’s willingness to return capital.
- MetLife’s diversified business model — spanning group insurance, retirement solutions, and institutional asset management across multiple geographies — provides a degree of resilience against any single segment or regional downturn.
Points of attention and risks
- The trailing P/E of 18.33 stands notably higher than the forward P/E of 8.78, and EPS growth is reported at a negligible 0.01, raising questions about the consistency and durability of near-term earnings improvement.
- The range of analyst price targets is wide, from $84 to $119, reflecting genuine uncertainty about the outlook; the lowest target implies meaningful downside from the current price.
- One analyst carries a strong sell rating, a reminder that not all market participants share the broadly positive consensus view.
- As a large life insurer, MetLife is sensitive to changes in interest rates, credit spreads, and equity market levels, all of which can affect both investment income and the valuation of policyholder liabilities.
- The company’s significant international exposure — particularly in Asia and Latin America — introduces currency and geopolitical risks that can weigh on reported earnings in periods of US dollar strength or regional instability.
Analyst consensus and price targets
Conclusion
MetLife enters the second half of 2026 with a solid recent earnings record, a meaningful buyback programme, and a valuation that appears undemanding on a forward basis. The broadly positive analyst consensus and strong momentum score are notable, though the wide dispersion of price targets and the near-zero trailing EPS growth rate are reminders that execution and macroeconomic conditions — particularly interest rates and currency moves — will be important variables to watch. Investors may find the combination of income characteristics, capital returns, and relative valuation worth examining as part of a diversified financial-sector allocation.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 24-08-2026. Not investment advice.